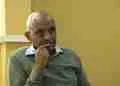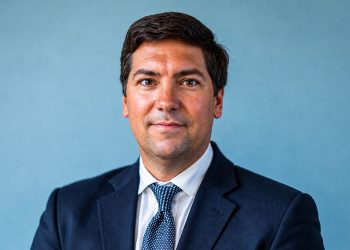

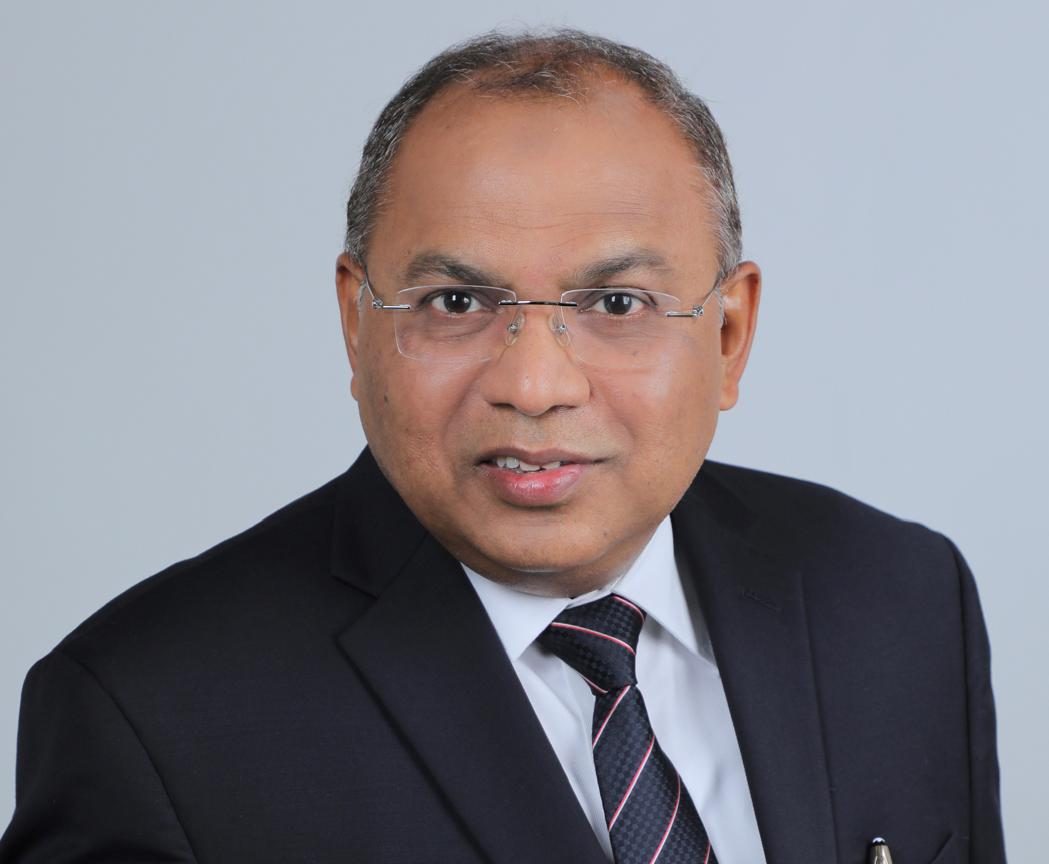

Aslam Allugundu is a veteran of the aviation industry, with a career stretching more than 30 years across some of the world’s largest airlines, including Qatar Airways and Emirates, airports, cargo operators, and aviation technology firms.
Allugundu has led complex transformation programmes spanning airport development, operational readiness, enterprise modernization, platform commercialization, and ecosystem integration. His experience combines strategic vision with hands-on execution, helping organizations align governance, commercial objectives, operations, technology and partnerships to deliver sustainable long-term value.
Today, Allugundu works as an independent advisor, offering his invaluable perspective and expertise on how aviation ecosystems evolve, integrate and scale to achieve operational excellence, commercial resilience, and institutional maturity.
RELATED POSTS
The Reporter Magazine’s Yared Nigussie spoke with him for a deeper look into the challenges and operational hurdles facing aviation today, particularly in relation to airlines across Africa and the Middle East.EXCERPTS:
The Reporter Magazine:Ethiopian Airlines and Qatar Airways both hold strong positions in the Middle East segment—Qatar dominating long-haul premium routes from major Gulf hubs, and Ethiopian building a solid footprint in key labor and regional corridors. How does Qatar Airways view Ethiopian Airlines’ growing presence in these secondary markets, and where do you see the primary points of competition between the two carriers?
Aslam Allugundu: I would not characterize this simply as a competition between Ethiopian Airlines and Qatar Airways. The network architecture and strategic priorities of the two airlines are quite different.
Qatar Airways and Emirates operate predominantly through a global hub model, with Doha and Dubai connecting major East-West and North-South flows across Asia, Africa, Europe, North America and Australia. Ethiopian Airlines has a different structural proposition, with Addis Ababa functioning primarily as an Africa-centered hub, aggregating traffic from across the continent and connecting it onward to Asia, the Middle East and Europe.
Therefore, as Ethiopian expands deeper into Tier-2 Middle Eastern cities such as Sharjah, Abu Dhabi and the secondary Saudi markets, I would expect the more direct competitive overlap in some markets to be with airlines connecting these secondary Middle Eastern cities into secondary African markets through their respective hubs. This could be more relevant to carriers such as Fly Dubai, Air Arabia and flyadeal than to the core global-hub proposition of Qatar Airways or Emirates.
Hence, I would be cautious about interpreting Ethiopian’s expansion simply as taking market share from Qatar Airways. There will undoubtedly be competition on individual routes and passenger flows, but the two airlines are fundamentally monetising different network structures.
The important question for Ethiopian as it continues to grow is whether its institutional and commercial maturity can sustain this competition as the competitive landscape evolves. The competition will not come only from regional Middle Eastern airlines. It can increasingly come from European carriers and, importantly, from African airlines themselves. Kenya Airways, for example, is pursuing significant new funding to support its turnaround and future fleet and network expansion.
ForEthiopian, therefore, the real test is not defending against any one competitor, but continuously adapting its network and commercial model as the competitive environment changes and sustaining the value of the asset base it has built.
Qatar Airways appears to be investing heavily in new markets, notably acquiring a 60 percent stake in Kigali’s new international airport alongside a 49 percent stake in RwandAir. Some view this as a strategicdefensive counter to Ethiopian Airlines’ regional footprint. What is your take on this?
I would not view Qatar Airways’ investment in Rwanda purely as a defensive move against Ethiopian Airlines. Large, financially strong airlines increasingly use equity investments and partnerships not only for financial returns, but also to extend their network reach and strengthen their strategic position in important markets.
Qatar Airways itself is a good example. Its investment in International Airlines Group (IAG), the parent group of British Airways and Iberia, is a significant strategic equity investment. In other markets, the logic can be different. An investment in an emerging airline can potentially provide access to a local or regional network that can feed traffic into a major global hub such as Doha.
Rwanda is particularly interesting in this context. The 60 percent interest in New Kigali International Airport, originally held by Qatar Airways, was transferred to Qatar Investment Authority on 1 June 2026. The Qatar Investment Authority [QIA] is Qatar’s sovereign wealth fund and has committed substantial additional capital to complete the airport. I would therefore see this increasingly as a long-term investment in African aviation infrastructure, with both economic and strategic implications, rather than simply a Qatar Airways response to Ethiopian.
What is also interesting is that Ethiopian Airlines is pursuing a broadly comparable model within Africa through investments and partnerships involving ASKY, Malawi Airlines, Zambia Airways and Air Congo. These arrangements can bring more than capital. They can bring aircraft, management capability, operating processes, training, Maintenance, Repair and Overhaul [MRO] and network connectivity.
For emerging aviation markets, that institutional capability can be as important as the capital itself. The ability to transfer proven aviation management and operating maturity into a developing market is what can ultimately turn an airport, airline or fleet investment into a sustainable aviation ecosystem.
The competitive implications for Ethiopian are therefore real, but I would distinguish competitive consequence from competitive intent. These models are likely to become increasingly important as more capital and experienced aviation institutions enter Africa.
Could you please explain the difference between competitive intent and competitive consequence?
Competitive intent is when an airline makes an investment or takes a particular strategic decision with the intention of creating a competitive advantage, entering into competition, or beating an existing competitor. An airline knows that there’s a competition in the market and decides to invest in order to compete more effectively or create a stronger competitive position.
Competitive consequence is different. In this case, the airline’s primary intention is not necessarily to compete with another airline. Its objective may simply be to grow its business, expand its network, invest in a particular market, or improve profitability. However, as a consequence of that investment or expansion, its activities may affect other airlines and create a competitive situation.
In competitive intent, an investment is made specifically with the intention of creating or responding to competition. In competitive consequence, the intention is to grow the business or achieve another commercial objective, but that growth subsequently creates a competitive impact on other airlines.
The example of Qatar Airways’ investment in Rwanda illustrates this distinction. In my view, Qatar Airways’ investment in Rwanda is not necessarily intended to create competition for Ethiopia. Rather, the objective is to invest in Rwanda, contribute to the development of the country’s aviation sector, and benefit from the opportunities created by integrating Rwanda into its global network.
If Rwanda’s aviation sector grows significantly and Kigali Airport develops into a larger aviation hub, that could eventually create a competitive consequence for Ethiopia. But that would be a consequence of Qatar Airways’ investment rather than its primary intent. The first is competitive intent; the second is competitive consequence.
Ethiopian Airlines has roughly USD 45 million stuck in Russia due to SWIFT restrictions and banking sanctions in the wake of the Ukraine-Russia war. When primary banking channels are completely severed, what legal mechanisms—such as bilateral trade clearings, local operational offsets, or state-backed barter systems—can an international airline utilize to extract or deploy those revenues without triggering secondary Western sanctions?
The Russia case is quite different from the more conventional foreign-exchange blockages that airlines face in some African markets. Ethiopian Airlines is one of the airlines affected, with around USD 45 million reportedly trapped in Russia following the disruption of normal international banking channels.
Like any airline, Ethiopian can pragmatically use locally generated rubles for eligible local operating expenses such as fuel, salaries, ground handling and other services. This can reduce the accumulated balance, but it cannot realistically eliminate the entire exposure. The more difficult issue is how to deal with the residual funds.
This is where the Russia situation requires a much higher level of caution. Any alternative settlement mechanism has to be assessed against the applicable sanctions and banking regulations, including the United States and European sanctions. For an international airline, compliance cannot be treated separately from commercial decision-making because its banking relationships, aircraft suppliers, lessors, insurers and other international partners can all be affected.
I, therefore, see this less as an airline trying to solve a banking problem on its own and more as an issue requiring engagement between the airline, its government and the relevant Russian authorities through appropriate diplomatic and bilateral channels. Where permitted by law, alternative settlement or utilization mechanisms can be considered, but strictly within a compliant framework. There is also a broader commercial question. Financial maturity has to work alongside network and commercial maturity. If the economics of operating in a market are materially altered by sanctions, currency or repatriation constraints, the airline has to continuously reassess whether to maintain frequencies, reduce capacity or, where necessary, suspend the route. In some cases, however, maintaining connectivity may also have a wider sovereign or bilateral significance beyond the airline’s purely commercial calculation.
In sanctioned markets where cash cannot be repatriated, airlines often spend local currency on local fuel, catering, and crew accommodations. What are the operational limits of this strategy, and does relying on local spending leave carriers dangerously exposed to rapid currency devaluations?
Blocked airline funds arising from foreign-exchange shortages are not a new phenomenon. This has been a longstanding issue in several markets, particularly in Africa. Nigeria is a well-known example. At one stage, its blocked airline funds reached around USD 850 million, with serious consequences for airline operations and connectivity.
The scale of the current problem remains significant. The International Air Transport Association (IATA) reported USD 1.2 billion of airline funds blocked globally at the end of October 2025, with 93 percent concentrated in Africa and the Middle East. Ethiopia is also part of this picture, with around USD 40 million currently reported as blocked for airlines operating in Ethiopia.
Using local currency for legitimate local expenses is therefore a well-established and pragmatic mechanism. Airlines can use it for salaries, handling, airport charges, catering and other local costs. Where commercially and operationally appropriate, fuel uplift can also absorb some additional local currency exposure. But these mechanisms can only consume part of the revenue, and the residual balance remains exposed to currency depreciation and loss of value.
This is where the issue moves beyond the treasury. A mature airline also considers the commercial structure of the route: how fares are distributed, where payments are collected, which currencies are encouraged, the balance between local and externally generated revenue, and the overall economics of the route.
Ultimately, the question is whether the route remains viable after considering the cost of trapped capital and currency risk. The response may be to maintain the operation, reduce frequencies, redeploy capacity or, if the economics no longer support it, suspend the route. Treasury maturity, commercial maturity and network economics therefore have to work together.
Blocked funds are becoming a major problem in the aviation industry. Airlines tend to prefer paying for global brokers to get their blocked funds abroad. Do you consider this a necessary commercial activity or a risky precedent?
Foreign exchange availability is ultimately a matter of national priority. In many countries facing its shortages, essential imports such as fuel, food, medicines and other critical requirements naturally receive priority. Aviation is economically important because it enables trade, tourism and connectivity, but airline revenue repatriation may not be at the top of the foreign exchange allocation queue.
This is where intermediaries or specialized brokers can sometimes emerge. They may assist airlines and other businesses in finding lawful mechanisms to recover or transfer trapped funds. But I would not describe using a broker as inherently necessary or risky. It is a commercial decision that has to be assessed case by case.
For an airline, the decision should involve treasury, compliance and legal functions, considering the quantum of funds, recovery cost, intermediary credentials, payment route, applicable sovereign and sanctions requirements, and the overall risk-reward equation.
The cost can also be significant. If an airline pays a substantial premium to recover funds, management has to compare that cost with leaving the funds trapped and exposed to further currency depreciation.
So, from a practitioner’s perspective, I would not recommend a blanket approach. The mature approach is a documented, risk-based decision on each case, with treasury, commercial, compliance and legal considerations working together.
Qatar Airways gets spare parts from both Airbus and a wide network of other specialized aerospace suppliers, original equipment manufacturers, and maintenance providers. Because airlines operate mixed fleets involving multiple manufacturers, they source components from primary airframers as well as independent parts distributors and engine makers. Airframe and engine OEMs often attempt to lock airlines into exclusive, long-term maintenance power-by-the-hour (PBH) agreements or proprietary parts networks. How successfully can top-tier global airlines resist OEM lock-in by using third-party component pools and independent MRO vendors to keep parts procurement competitive?
I would see Power-by-the-Hour arrangements for engines, Auxiliary Power Unit [APUs] and other critical components as a well-established industry practice rather than something specific to Qatar Airways or any particular airline. The important question is how effectively the airline negotiates and manages those agreements.
The real leverage comes from having a mature specialist contracting team that understands aircraft, engines and MRO, and can be creative in structuring the terms. Fleet size and order value obviously provide negotiating power, but the contractual architecture is equally important. This includes exclusivity, benchmarking rights, performance guarantees, flexibility to renegotiate, termination provisions and the ability to introduce alternative MRO providers where appropriate.
Many mature airlines have specialist aircraft and component contracting functions, often involved from the aircraft acquisition and delivery stage. Their ability to use fleet scale, commercial value and long-term OEM relationships can materially improve the outcome of these contracts.
The second dimension is the airline’s own MRO capability. The balance between what can be handled internally and what is contracted to OEMs or independent MRO providers directly affects the airline’s negotiating leverage and operational flexibility.
There is also a known industry issue when long-term PBH arrangements expire, particularly around the remaining value and condition of components and the obligations attached to them. That needs to be considered when the contract is structured, not only when it expires.
So, I would see two principal maturity factors—the quality and flexibility of the contractual framework, and the airline’s internal MRO capability and external MRO options. The overall commercial leverage then comes from combining these capabilities with the airline’s scale and purchasing power.
Drawing from your experience at Qatar Airways, where rapid growth was fueled by aggressive fifth-freedom traffic rights and open skies, how can African governments break the cycle of air transport protectionism?
I would not attribute the growth of Qatar Airways, or similar global hub carriers, primarily to fifth-freedom traffic. Their fundamental growth model is sixth-freedom connectivity, using a global hub to aggregate traffic from different regions and connect East-West and North-South flows.
Fifth-freedom sectors are a different proposition. Emirates has historically used them more extensively, while Qatar Airways has also used selected fifth-freedom routes. These are essentially commercial tools to make a particular sector viable where local origin-and-destination demand may not be sufficient.
I, therefore, see fifth freedom primarily as a network-planning and route-economics decision, rather than a growth strategy for the airline. Network planning and revenue management assess demand, connecting flows, capacity, yields and route economics to determine whether an intermediate market adds value, subject to the necessary bilateral rights.
From an African country’s perspective, there can also be significant value in appropriately structured fifth-freedom opportunities. Many African markets may not individually generate sufficient demand for direct long-haul services. Aggregating traffic between two markets can make a service commercially viable while improving connectivity.
Where the commercial case exists and bilateral arrangements permit it, African countries should therefore be open to fifth-freedom opportunities as a practical connectivity tool.
Is the Single African Air Transport Market (SAATM) failing due to a lack of enforcement mechanisms, or are national flag carriers actively lobbying against open skies to survive against dominant players like Ethiopian Airlines?
I see SAATM as a very important and necessary initiative for Africa. If fully implemented, it can create a much better-connected African aviation market, supporting travel, tourism, trade, economic development and connectivity with the wider world.
The challenge, however, is implementation at the state level. SAATM has an institutional enforcement and execution framework through African Civil Aviation Commission [AFCAC], including monitoring, dispute mechanisms and, where applicable, penalties. The greater challenge is translating those continental commitments into consistent national implementation. Individual countries have their own economic, political and national-carrier priorities. This is where protectionism, regulatory processes and bureaucratic delays can slow progress. AFCAC itself works with national civil aviation authorities and other State-level stakeholders to address these implementation gaps. I also think Ethiopian Airlines, given its scale and position in African aviation, can play a larger leadership role in demonstrating the benefits of liberalization and encouraging other African carriers and governments to participate more actively.
Ultimately, SAATM is the right direction. The objective now should be to move from commitment to implementation and from implementation to measurable connectivity and economic value. AFCAC, governments and African airlines all have a role in making that transition happen.
African governments have often been blamed for the demise of many airlines on the continent. Do you think there is adequate political will to revive the aviation sector in the African continent?
There is a clear direction across the continent. Countries are investing heavily in aviation infrastructure, through both airport expansions and new greenfield developments. We are seeing this across Ethiopia, Rwanda, Morocco, Egypt, Senegal, Tanzania, Uganda and several other markets. The significant aircraft orders across African airlines, with 200 plus aircraft already on order, also indicate that the underlying growth opportunity is being recognized.
The bigger question is whether the institutional environment can convert this investment into sustainable aviation value. Airlines need access to capital and foreign exchange not only to acquire aircraft, but also to support OEM obligations, MRO and operations. At the same time, governments have competing priorities for scarce foreign exchange.
Governance and institutional independence are equally important. Ethiopian is an interesting example of a government-owned airline where the board and management have historically had considerable operational and commercial independence, while a wider aviation ecosystem has developed around it, including airports, MRO and an aviation academy. That combination of government support and institutional capability has been important to its development.
South African Airways provides a useful contrasting experience, where changes in leadership, strategy and the relationship with government have affected continuity.
Africa has different models available: a well-governed national airline, a Public Private Partnership structure, or private operators supported by an enabling regulatory, taxation and investment environment.
Ultimately, Africa has a significant connectivity gap relative to its population and economic potential. The role of governments and sovereign civil aviation authorities is not simply to provide capital or build infrastructure, but to create the policy, regulatory and governance environment in which airlines can develop the institutional capability and maturity to sustain that investment and convert it into long-term connectivity and economic value.