For nearly three years, one rule shaped how Ethiopia’s banks could lend: annual private-sector credit growth could not exceed the ceiling set by the National Bank of Ethiopia (NBE). That chapter has now closed. But replacing one of the country’s most consequential monetary policy tools has opened a more difficult question: what happens next?
Will credit become easier to obtain? Will higher borrowing costs keep inflation under control? And where will banks direct newly available lending?
Announcing its latest monetary policy decisions on July 13, the NBE said improving macroeconomic conditions had created room to replace direct lending controls with market-based monetary policy. The Monetary Policy Committee removed the 24 percent annual private-sector credit growth cap, raised the policy rate to 16 percent, introduced targeted reserve requirements for commercial banks, reduced exporters’ foreign exchange surrender requirement from 50 percent to 30 percent, and lowered foreign exchange transaction commissions from 2.5 percent to 1.5 percent.
RELATED POSTS

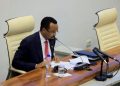
Governor Eyob Tekalign (PhD) described the package as “a change in instrument, not a change in stance,” saying the central bank would increasingly rely on policy rates, reserve requirements and liquidity management operations to maintain price stability.
Whether the new framework can deliver that objective is now the central question.
Will Credit Become Easier to Obtain?
The removal of the credit cap has fueled expectations among businesses and borrowers that access to finance will improve almost immediately. Sewale Abate (PhD), assistant professor at Addis Ababa University and deputy board chairperson of Zemen Bank, says the change should not be interpreted as a solution to Ethiopia’s long-standing financing gap.
“It won’t be like that,” Sewale said. “One misconception is that simply lifting the credit cap will solve the liquidity supply problem. However, the gap between financial supply and demand in the economy is extremely wide.”
Even before the credit restrictions were introduced, annual deposit and loan growth averaged around 30 to 35 percent, Sewale says. Since the ceiling had already been raised to 24 percent before it was removed, “the change we will see now is marginal.”
He adds that banks cannot lend all the deposits they mobilize because they must maintain regulatory reserves. Against what he describes as the economy’s “financial hunger,” the additional lending capacity created by removing the cap will still fall well short of demand.
“Given the financial hunger in the market, the lifting of the cap is not expected to increase supply as significantly as people think,” Sewale told The Reporter Magazine.
Eshetu Fantaye, a banking veteran on his part notes, “Having worked in a banking environment, I don’t see my colleagues going for rapid expansion of bank lending automatically. The cap removal gives banks permission to lend more, but it does not give them more deposits.”
He also said the NBE’s new reserve requirement framework would discourage excessive lending relative to banks’ funding capacity.
“The NBE’s new bank-specific reserve requirements tied to loan-to-deposit ratios act as a natural brake. Banks that expand lending faster than they mobilize deposits will face higher reserve obligations,” he said. “I expect lending growth to accelerate, but not explosively.”
Where Will Banks Put Their Money?
The removal of the private-sector credit growth cap gives banks greater freedom to decide how to deploy their funds. But whether that translates into more lending depends on the alternatives available to them.
Those alternatives remain significant. Parliament has approved a record 2.34 trillion birr federal budget for the 2026/27 fiscal year, with 320 billion birr expected to be financed through domestic borrowing. At the same time, Treasury bills have become an increasingly important instrument in Ethiopia’s transition to an interest-rate-based monetary policy framework. The IMF has repeatedly stressed that developing a market-based government securities market is central to that transition while calling for close monitoring of private credit growth as monetary policy shifts away from administrative controls.
Eshetu does not expect banks to abandon government securities in favor of private lending alone. The government’s planned domestic borrowing, he says, means it will remain “a large and reliable borrower,” while Treasury bills continue to offer banks “a risk-free return with zero provisioning requirements.” As a result, “that gravitational pull does not disappear because the credit cap has been lifted.”
What has changed, in his view, is the range of choices available to banks. Under the previous framework, he notes, “banks had no choice; they could not lend beyond the ceiling, so excess liquidity had nowhere to go except government paper.”
With the cap removed, banks can once again “weigh the risk-adjusted return on a loan to a manufacturer or exporter against the yield on a Treasury bill.” Even then, he cautions against expecting an abrupt shift.
“Banks will not abandon government securities overnight, nor should they,” said Eshetu.
A former university business lecturer, banking professional and investor educator, who spoke anonymously, expects commercial banks to expand lending because it remains their primary source of income and profitability. But unlike the years when lending growth was constrained by regulation, he believes banks will now compete more aggressively to mobilize deposits.
“I also expect stronger competition for deposits,” he says, adding that banks are likely to offer more attractive rates on fixed-term deposits to finance additional lending, particularly as Treasury bills have become an alternative investment option.
He likewise expects Treasury bills to play a different role than they did under the credit cap. Rather than replacing private-sector lending, they have become “a genuine market-based instrument rather than a mandatory investment for financial institutions.” Because private-sector lending generally offers higher returns than government securities, he expects banks to continue prioritizing loans while using short-term Treasury bills “to manage excess liquidity.”
The IMF’s latest projections also underscore the importance of the Commercial Bank of Ethiopia (CBE) in the transition. The Fund forecasts 24.8 percent growth in credit to the private sector and state-owned enterprises during 2026/27, explicitly incorporating the expected impact of CBE’s recapitalization. CBE has also announced plans to set aside about 1.09 trillion birr for lending during the 2026/27 fiscal year, highlighting the scale of its expected contribution to overall credit expansion.
Eshetu argues that CBE’s role is decisive, not only because of its size but also because its lending decisions are likely to influence the wider banking sector. If the bank channels more financing toward productive sectors, he says, the removal of the credit cap could deliver the intended growth dividend while encouraging private banks to follow. If, however, CBE continues to absorb much of the government’s domestic borrowing while limiting private-sector lending, the underlying imbalance in credit allocation could persist despite the policy shift.
Can the New Framework Keep Inflation in Check?
With the private-sector credit growth cap now removed, the next question is whether the National Bank’s new monetary policy framework can keep inflation under control.
The banker argues that the July 13 reforms should be assessed as a package rather than as individual measures. He describes the removal of the credit growth cap as a logical step in Ethiopia’s transition toward a more market-based monetary policy framework, but notes that, on its own, it could increase money supply and inflationary pressure. Combined with the higher policy rate and targeted reserve requirements, however, “these measures create a more balanced framework where monetary policy relies less on administrative controls and more on market-based instruments.”
Sewale shares a similar assessment. He expects the removal of the credit growth cap to increase financing by allowing banks to put previously idle liquidity to productive use. At the same time, he cautions that stronger credit growth also carries inflationary risks.
“On the flip side, however, it carries the risk of worsening inflation. To control this, the National Bank will use other monetary policy instruments, such as Treasury bill sales and Targeted Reserve Requirements. By utilizing these, I believe the National Bank can manage inflation at an acceptable level,” he told The Reporter Magazine.
How quickly those instruments influence borrowing costs, however, is less certain.
“Because the monetary policy transmission rate to the market in our country is very weak, I do not believe it will have a major impact in the short term,” Sewalle says. “That said, lending interest rates have already increased. Some that were at 16 to 18 percent have now reached 21 percent. This is due to the imbalance between supply and demand.”
Eshetu likewise describes the July 13 reforms as “a significant and welcome step,” agreeing with the central bank governor’s characterization of the changes as “a change in instrument, not a change in stance.”
He argues, however, that while the NBE has strengthened the monetary framework, it has yet to create incentives that encourage banks to direct additional lending toward productive sectors.
“Removing the cap frees banks to lend, but it does not steer that lending toward exporters, manufacturers, and agribusinesses. Without incentive-based mechanisms, the risk is that freed-up credit flows disproportionately toward trade finance and real estate, where returns are faster and collateral is simpler,” said the banking veteran.
Eshetu argues that the central bank’s targeted reserve requirements serve a different purpose from the incentive-based framework he has proposed. “The loan-to-deposit ratio is sector-blind; it treats a bank lending heavily to importers the same as one lending heavily to manufacturers, provided both are within their deposit-supported capacity.”
He therefore recommends complementing the prudential framework with incentives for banks that lend to exporters, manufacturers, agribusinesses and small and medium-sized enterprises.
Eshetu says similar approaches have already been adopted elsewhere in East Africa. He points to Tanzania’s reserve requirement relief for qualifying agricultural lending and Uganda’s Agricultural Credit Facility as examples of how central banks can encourage lending to productive sectors without relying on blanket credit restrictions.
Sewale, however, takes a more cautious view of attempts to steer commercial-bank lending. He argues that banks should allocate credit according to their own lending policies and the commercial viability of borrowers, particularly as Ethiopia moves toward greater financial liberalization.
“Loan allocation is carried out according to each bank’s individual credit policy,” he says. “Banks lend to sectors that are business-viable.” Where the government wants to support priority sectors, he adds, specialized institutions such as the Development Bank of Ethiopia are better placed to provide that financing.
The banking professional also cautions against assuming that directing additional credit toward manufacturing or agriculture will automatically translate into stronger productivity and lower inflation. While increased financing could support supply expansion in principle, he notes that Ethiopia’s manufacturing sector continues to face structural inefficiencies and relatively low returns.
“Unless those underlying challenges are addressed,” he says, “simply increasing credit to manufacturing may not deliver the expected productivity gains.”
Concerns that easier access to bank credit could fuel another surge in property prices have also accompanied the removal of the credit growth cap. Eshetu, however, argues that the role of bank lending in Ethiopia’s real estate market should not be overstated.
“Rising property and real-estate prices are a legitimate concern, but they are driven more by structural factors, urbanization, limited housing supply, diaspora remittances, and the absence of alternative investment vehicles, than by bank credit policy. The credit cap did not prevent property prices from rising over the past three years; removing it will not be the primary driver of further increases,” he told The Reporter Magazine.
Even so, he says the NBE should monitor where additional lending is being directed.
“If a disproportionate share of new lending flows into real estate speculation rather than productive investment, macro prudential tools such as loan-to-value limits and higher risk weights on property lending should be deployed. Kenya and Rwanda both use these tools effectively.”
The banking professional also expects stronger credit growth to support some increase in property prices, although he believes broader economic conditions will limit the extent of any rise.
“I do expect some upward movement in property prices following stronger credit growth, but probably not to the extent many people anticipate,” he says. “Household purchasing power has weakened considerably, while higher taxes, fees and borrowing costs are likely to moderate any significant increase in property prices.”
Beyond bank lending, observers caution that policymakers should also monitor borrowing outside the formal banking system.
“Many microfinance institutions and SACCOs already lend at rates well above 30 percent. Businesses facing liquidity shortages may still be willing to borrow at these high costs and pass the additional financing costs on to consumers through higher prices. If that behavior becomes widespread, it could weaken the effectiveness of the broader monetary policy framework.” the anonymous banker told The Reporter Magazine.
Eshetu agrees that higher borrowing costs can contribute to inflation but argues that the effect should be kept in perspective.
“The concern is legitimate but needs to be placed in proportion,” he says. “The cost-push effect of a 16 percent policy rate is real but bounded; the supply-side damage of credit rationing is open-ended.”
While businesses may attempt to pass financing costs on to consumers, he argues that firms unable to secure working capital reduce output instead, worsening the supply shortages that also drive inflation.
Sewale identifies another risk if newly available credit is diverted away from productive investment. “Another risk is that if people take loans from banks and use them to hoard foreign currency in the black market, inflation could worsen. Therefore, strict monitoring is required.”
Can Gold Operations Undermine the New Monetary Framework?
While much of the attention surrounding the National Bank of Ethiopia’s latest monetary policy package has focused on the removal of the credit growth cap and higher interest rates, another issue has drawn the attention of both the NBE and the International Monetary Fund: the liquidity created through the central bank’s domestic gold purchases. The IMF’s Fifth Review says reserve money growth accelerated to 67 percent year-on-year in March 2026, up from 43 percent in February, driven largely by the central bank’s gold purchases. The Fund also notes that liquidity has become increasingly concentrated at the Commercial Bank of Ethiopia and has called for improvements to the NBE’s gold market operations.
Eshetu says the IMF’s findings point to a structural challenge for Ethiopia’s new monetary policy framework because gold purchases inject liquidity outside the normal credit channel.
“If the NBE is simultaneously tightening through a 16 percent policy rate and loosening through large-scale Birr payments for gold, the net monetary stance becomes ambiguous. This is a structural issue that rate adjustments alone cannot fully resolve.” he told The Reporter Magazine.
He argues the solution lies not in additional monetary tightening, but in improving the way the National Bank manages its gold operations. “The NBE should publish a transparent framework for its gold operations, including purchase volumes, pricing methodology, and sterilization mechanisms.”
He also says liquidity created through reserve accumulation should be sterilized to preserve the credibility of the new framework. “Without that discipline, gold operations risk becoming a backdoor source of monetary expansion that undermines the credibility of the interest-rate-based framework the NBE has just adopted.”
The banking professional likewise says the key question is whether the NBE can successfully absorb the liquidity created by its gold purchases.
“The effectiveness of the current framework will depend on whether the National Bank can offset these liquidity injections through policy rates, reserve requirements and open market operations. If those instruments are used effectively, the inflationary impact can be contained. If not, liquidity created through gold purchases could undermine inflation control efforts.”
On the other hand, Sewale argues that the resulting increase in money supply is already being managed through other monetary policy instruments.
“The central bank uses T-Bill sales and the policy interest rate to manage the money supply created as a result. It is an effort to solve a problem on one side by addressing it on the other.” he told The Reporter Magazine.
What Will Determine Success?
The experts broadly agree that the latest reforms should be judged not by the removal of the credit cap alone, but by how effectively the new framework delivers its intended objectives. While each emphasizes different priorities, they point to the same underlying challenge: ensuring that stronger credit growth supports productive investment without undermining price stability. They also stress that monetary policy will need to be complemented by sound fiscal coordination, effective supervision, transparency and broader structural reforms.
Looking ahead, Eshetu says the clearest indication that the transition is working will be whether a larger share of bank lending reaches productive sectors rather than trade and real estate, while inflation remains broadly contained, the interbank market begins transmitting the policy rate more effectively, banks respond to the new reserve requirement framework by mobilizing deposits rather than simply slowing lending, and recent foreign exchange reforms help narrow the gap between the official and parallel markets.
The banking professional likewise argues that policymakers should closely monitor how credit is allocated across the economy, financing conditions outside the banking sector, and governance and transparency within the financial system. Together, they suggest these indicators will provide a clearer picture of whether Ethiopia’s transition from quantity-based to market-based monetary policy is achieving its intended objectives.
For Eshetu, however, the direction of the reforms is no longer the central question. “The direction of travel is right. What matters now is the quality of execution.”