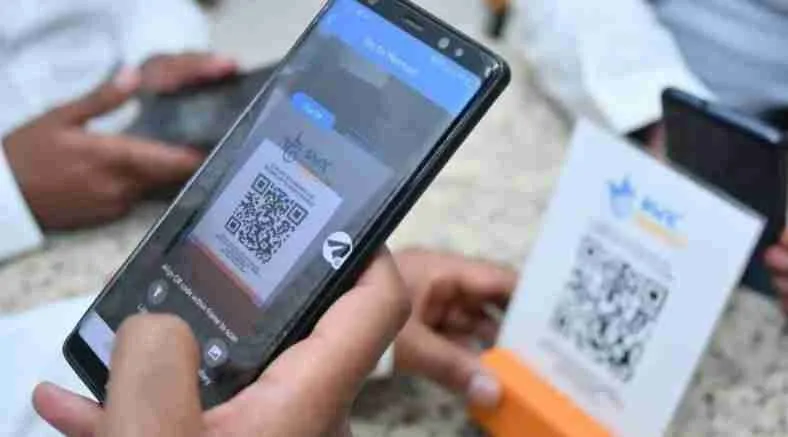

On a busy afternoon in Addis Ababa’s Bole neighborhood, shop owner Hana Tesfaye, 31, stood impatiently beside an ATM machine that had once again run out of cash before her turn arrived. Frustrated and pressed for time, she reached for her mobile phone instead, transferring money digitally to pay for a supplier waiting across town. The transaction took only a few seconds, but by the time the transfer was completed, a series of deductions had quietly reduced the amount she intended to send.
“At first digital banking felt modern and convenient,” she said. “Now it feels like every transaction comes with a fee.”
She paid a transaction fee of 70 Birr to transfer 13,000 Birr to the state-owned Commercial Bank of Ethiopia (CBE) from one of the private banks, including service charge and value added tax (VAT). She is far from the only one paying these fees every day.
RELATED POSTS


Ethiopia’s push toward a digital economy has accelerated rapidly over the past decade. Mobile banking, app-based transfers, USSD services, and digital wallets such as Telebirr have altered the way people send and receive money. In 2024/25, national switch operator EthSwitch reported that digital transactions had surpassed ATM withdrawals for the first time.
Despite the progress, a growing number of consumers say the convenience of digital finance is being overshadowed by rising service charges, transfer deductions, and ATM withdrawal fees that are placing additional pressure on households already coping with intense inflationary pressure.
Amanuel Sileshi, another digital banking service user, is among the millions of digital banking users in Ethiopia who are growing more and more frustrated with the fees he is forced to pay each day.
“The digital transaction fees are unreasonable and one of the banks I use even charges me a monthly maintenance fee from my savings account without my consent, which is illogical,” he told The Reporter Magazine. “I’m discouraged from using the bank, and considering withdrawing my deposits entirely.”
He notes that Ethio telecom’s popular Telebirr mobile money platform, which has facilitated transactions valued at over seven trillion Birr since its launch in 2021, also charges fees on every transaction.
“The daily fees discourage people from using banks and digital payment systems,” said Amanuel.
For many Ethiopians, especially low-income earners, the fees feel excessive and unfair. Critics argue that they discourage digital adoption and reinforce the perception that financial institutions are profiting at the public’s expense.
A banking technology expert who spoke to The Reporter Magazine anonymously highlighted a growing structural problem within the ever-changing financial ecosystem.
He argued that excessive interbank transaction fees are discouraging digital banking adoption and placing growing pressure on small financial institutions, describing the issue as an imbalance between the value being transferred and the cost of sending it.
The expert believes that fees pertinent to relatively small transfers have reached levels that make digital transactions economically irrational for ordinary users. To illustrate his point, he used the example of a digital transfer of 180 Birr.
By the time the transaction is routed through the banking—particularly though the CBE—the associated processing cost climbs to 150 Birr. That fee is then split between participating institutions, with one entity receiving roughly 100 Birr and another taking the remaining 50 Birr.
“When you have to spend 150 Birr to transfer 180 Birr, the cost of the service practically swallows the actual income or capital being moved. It makes absolutely no economic sense for small transactions,” said the expert.
On his part, a branch manager working for one of the 30 private commercial banks balanced genuine enthusiasm for the technology with a stark warning about its financial burden on consumers. While agreeing that digital systems, from government transport to mobile banking, offer undeniable convenience, the manager acknowledged a growing complaint: service charges are simply too high.
Currently, a typical digital transaction incurs not only a base fee but also 15 percent VAT and an additional service charge, turning a 100 Birr transfer into a 120 Birr expense—a full 20 percent premium. This heavy burden, he argued, falls squarely on consumers, raising the overall cost of living.
Yet he defended the banks’ position, explaining that commissions and service charges are essential revenue streams. Without them, financial institutions cannot sustain the massive investments required for digital infrastructure, license renewals, or competition with agile fintechs like Telebirr, Chapa, and Arifpay.
He noted that digital transactions now account for over 80 percent of daily banking volume in major cities like Addis Ababa, driven by consumer demand for speed and ease. Still, the hidden costs are fueling resistance. By contrast, he pointed out that transferring roughly 700 Birr through Telebirr costs as little as six Birr, highlighting a competitive gap.
The bank manager expects to see the fees associated with digital payments grow. Today, the bank he works for charges a five percent disaster risk fund fee, 15 percent VAT, and 0.2 percent of the principal for EthSwitch. For transactions above 10,000 Birr the bank levies a 15 Birr payment per transaction.
Industry experts further explain why digital banking infrastructure requires enormous investment from banks and payment providers. While traditional banking depends on physical branches and staff, digital finance relies on expensive backend systems, cyber security infrastructure, data centers, mobile integrations, payment switches, and continuous system maintenance.
When banks in Ethiopia first introduced USSD and mobile banking services over a decade ago, they spent years investing heavily with little immediate return.
Yigermal Meshesha, a financial sector specialist with over 16 years of experience in banking, said that many institutions absorbed these costs for well over a decade while waiting for customer behavior to shift toward digital platforms.
Now that digital transactions have become mainstream, banks are entering the phase where they expect returns on those investments.
“From this perspective, transfer fees, cash-out charges, and other service costs are viewed by institutions as necessary sources of revenue to sustain operations and continue expanding digital infrastructure,” he said.
Digital transaction pricing in Ethiopia falls into two categories, Yigermal says.
The first involves transactions routed through the national payment switch, which is EthSwitch. This includes interbank ATM withdrawals, point-of-sale (POS) payments, and person-to-person transfers between different financial institutions. In these cases, pricing is largely determined by the switch system itself, and banks are expected to adopt those rates.
The second category involves fees set directly by banks for services within their own ecosystems or for transfers to external platforms such as Telebirr or M-Pesa. These pricing structures are guided by the National Bank of Ethiopia’s tariff frameworks, including regulations tied to RTGS and automated transfer system (ATS) transactions.
Banks then incorporate their own operational expenses into the final customer fee.
Yigermal further explained that many of the public complaints stem not from internal bank transfers, but from transfers between different financial institutions or digital platforms. In such cases, the sending institution often pays fees to the receiving platform and passes those combined charges on to customers.
One of the strongest criticisms of Ethiopia’s digital finance ecosystem is the lack of transparency around pricing.
Customers often see only the total amount deducted without understanding how the fee is divided. Financial analysts argue that users should clearly see the bank’s service fee, the network switch charge, and any fee collected by the receiving platform.
Without that clarity, customers are more likely to feel exploited.
“The issue becomes especially sensitive during periods of high inflation. While middle-income users may consider a 10 or 20 Birr charge insignificant, low-income users view even small deductions as burdensome. This economic reality makes pricing highly sensitive in Ethiopia’s emerging digital economy,” Yigermal explained.
He believes Ethiopia should adopt a more aggressive subsidy model for micro-transactions, arguing that transfers within the range of 500 to 1,000 Birr should be free from charge to encourage mass digital adoption. Given that the majority of Ethiopians are highly price-sensitive, reducing transaction costs could significantly accelerate financial inclusion and reduce dependence on cash, observes the expert.
If digital services become too expensive, there is concern that people may revert to informal cash-based systems, slowing the country’s broader digitization agenda.
Regional comparisons present a mixed picture.
In countries such as Tanzania, Uganda, and Kenya, banks and mobile money operators often charge significantly higher fees across a wider range of services, including ATM withdrawals, checkbooks, transfers, and counter transactions.
Kenya’s M-Pesa, for example, is widely considered more expensive than Ethiopia’s Telebirr for many transaction categories. Analysts such as Yigermal say Ethiopia’s pricing, while unpopular domestically, remains comparatively moderate by regional standards.
The Central Bank of Kenya actively regulates mobile money costs to drive financial inclusion. For instance, inter-bank and intra-bank mobile transfers under 1,000 Kenya Shillings are mostly free, and regulators draft policies to further reduce average transaction costs across the board.
The NBE heavily regulates overall payment operations and has introduced caps on specific services, such as foreign exchange-related service fees of four percent. However, domestic peer-to-peer transaction fees are generally set by individual banking institutions and can vary significantly per transaction value.
At the same time, some African markets have adopted policies that completely waive fees for micro-transactions to encourage digital inclusion. These examples are increasingly influencing discussions around Ethiopia’s future pricing strategy.
Consumers have also expressed frustration over ATM withdrawal charges, especially when withdrawing relatively small amounts of cash.
Financial experts argue that cash itself is expensive to maintain.
“Printing currency, transporting it securely, insuring it, loading ATM machines, and maintaining nationwide ATM infrastructure have their own major operational costs,” said Yigermal.
Ethiopia’s ATM footprint is also unusually extensive compared to many African countries. ATMs are widely distributed and frequently stocked with cash, which increases security and maintenance expenses for banks.
As a result, many institutions increasingly prefer customers to shift toward mobile money and app-based payments, which are generally cheaper to manage over time.
Recent trends suggest that Ethiopia’s digital ecosystem is already moving decisively away from cards and toward mobile platforms.
Industry data indicates that active debit card usage has declined in recent years as more customers migrate to mobile banking and mobile money solutions. Expired cards are often not renewed, signaling changing customer preferences.
Today, mobile banking platforms—particularly those operated by major banks—handle the largest volume and value of digital transactions in the country. Experts say this transition creates both an opportunity and a challenge: banks must find pricing models that remain profitable while still affordable for ordinary Ethiopians.
Achieving that balance is increasingly seen as central to Ethiopia’s digital financial inclusion agenda.
Experts argue that Ethiopia’s fintech ecosystem cannot rely on payments alone.
Since the rise of African fintech in the late 2000s, digital payments have been the sector’s biggest success story. But the next phase of growth will depend on broader, more practical use cases that address everyday economic challenges.
Industry experts like Yigermal say Ethiopia now needs micro-savings tools, micro-loans, micro-insurance products, financial literacy services and more human-centered digital experiences designed for local realities.
Critics also argue that many current “super apps” are designed primarily for urban, tech-savvy users rather than the broader population.
To expand financial inclusion in a meaningful way banks and fintech companies may need to focus less on flashy interfaces and more on solving practical economic problems for ordinary citizens, small businesses, and low-income communities.
Ethiopia’s digital finance transition is clearly gaining momentum. Digital platforms save time, reduce dependence on physical cash, and create opportunities for broader financial inclusion.
But the debate over transaction fees highlights a critical tension of how to finance the costly infrastructure behind digital banking without alienating the very users needed to sustain it.