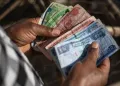


Gold has long carried a weight in Ethiopia that goes far beyond its shimmer. It has steadied reserves in moments of external strain, injected liquidity into the financial system, and quietly linked artisanal miners in remote regions to the core of the country’s monetary machinery. For decades, this precious metal has been a lifeline, a currency of trust, and a silent architect of both local livelihoods and national policy.
At the center of this intricate network stands the National Bank of Ethiopia (NBE), which for years has acted as the country’s dominant domestic buyer of gold. By offering premiums above international prices, the central bank drew supply into official channels, converting bullion into birr liquidity and anchoring both reserves and confidence in turbulent times.
That model is now set to change.
RELATED POSTS
In its fourth review of Ethiopia’s extended credit facility arrangement, the International Monetary Fund (IMF) noted that authorities have committed to phasing out the premium paid above international gold prices, allowing private banks to participate in gold purchases, and developing a long-term strategy for the NBE to exit direct participation in the gold market by December 2026.
The commitment is formalized in a Letter of Intent and Memorandum of Economic and Financial Policies submitted by the Ministry of Finance.
Beyond the headline commitment, the reform is already moving into its operational phase. According to the IMF, authorities plan to complete a detailed study in the coming month to guide implementation, including measures to strengthen quality testing across all gold purchasing sites and tighten transaction procedures. These interim steps are designed to reduce balance-sheet risks while preparing the market infrastructure needed for a gradual withdrawal of the central bank from direct trading.
The language of the IMF document is technocratic, but the implications are not.
If implemented as designed, the reform would redefine the role of the central bank, alter liquidity dynamics in the financial system, and shift control of a strategic export commodity into the hands of private intermediaries.
A Policy Born of Scarcity
The NBE’s involvement in gold purchasing was originally rooted in necessity. Faced with chronic foreign exchange shortages and high levels of gold smuggling, authorities introduced a premium system, at times offering up to 15 percent above international prices to attract supply into official channels.
The logic was straightforward. By offering miners and traders an incentive to sell domestically rather than across borders, the central bank could accumulate reserves and reduce illicit flows.
For a time, the system appeared to deliver. Official gold exports increased, and the NBE strengthened its reserve position during periods of external stress.
But over time, the costs mounted.
The gold reform is also tied to a broader effort to repair the central bank’s finances. The IMF notes that improving the NBE’s financial position is essential for strengthening its operational autonomy and restoring confidence in monetary policy.
A recapitalization plan, expected to be agreed with the Ministry of Finance by mid-2026, includes phasing out gold-purchase subsidies and reducing exposures that have weighed on the bank’s balance sheet. In this sense, exiting the gold market is as much an institutional reform as it is a sectoral one.
“The long-standing role of the NBE as the primary buyer of domestically produced gold has become a significant source of macroeconomic instability,” said Eshetu Fantaye, a veteran banking professional.
He observes the arrangement has evolved beyond a reserve-building tool into a quasi-fiscal operation with systemic consequences.
“It has resulted in significant quasi-fiscal losses, amounting to approximately 57.2 billion Birr in FY2024/25, and has contributed to inflationary pressures through a 71 percent expansion in base money,” he told the Reporter Magazine.
The banker added that the premium payment model required substantial money creation to finance purchases, reinforcing inflationary pressures and complicating macroeconomic management.
The IMF review reflects similar concerns, emphasizing the need to limit central bank operations that expand liquidity while strengthening an interest-rate-based policy framework.
Exchange Rate Distortions and Arbitrage
Gold purchasing did not occur in isolation. For years, Ethiopia’s official exchange rate diverged significantly from parallel market levels, and the premium system interacted with that distortion in complex ways.
Eshetu said the combination of an overvalued official rate and gold premiums created “misaligned incentives,” contributing to arbitrage and parallel market activity.
Recent exchange rate reforms appear to have shifted the landscape. Eshetu pointed to a surge in official gold exports following FX adjustments, noting that exports have reached nearly 39 metric tons.
The IMF review links gold reform to broader foreign exchange liberalization efforts, including auctions and reduced central bank intervention, positioning gold within a more market-based external framework. Authorities will now limit NBE intervention in the FX market to addressing disorderly conditions and “auctioning proceeds from gold purchases in excess of reserve accumulation objectives,” aligning liquidity management with reserve targets while maintaining orderly market functioning
Opening the Door to Private Banks
Perhaps the most transformative aspect of the reform is the decision to allow private banks to participate directly in gold purchases.
The move signals a philosophical shift. Rather than serving as a monopoly buyer, the NBE would transition toward regulator and supervisor, while licensed banks compete in sourcing, trading, and exporting bullion.
Regional mining authorities are already weighing the potential effects of the central bank’s planned exit.
Tujane Adem, head of the Benishangul-Gumuz Mining Bureau, said the NBE’s planned exit “will affect the market to some extent. Before the NBE started purchasing gold, the free market used to buy it, and much of it was smuggled across borders because buyers offered higher prices. When macroeconomic reforms began and the 15 percent premium was introduced, gold prices increased. I’ve also heard concerns that this exit could affect the central bank’s balance sheet. If the NBE fully exits and the premium is removed, I believe it will have some impact on the market. I am concerned whether private sector buyers or commercial banks will be able to provide the premium that the central bank used to give.”
Eshetu views the shift as both an opportunity and a risk.
On the opportunity side, he said banks could earn “new revenue from trading margins, fees, and FX generation,” and gold may serve as a “high-quality liquid asset.”
But he is candid about the system’s current readiness.
“Currently, private banks are not fully prepared,” he told The Reporter Magazine. “They lack the expertise in commodity trading, hedging, and the physical logistics of handling gold.”
He identifies three structural gaps:
“First, expertise. Building teams with skills in commodity risk management. Second, liquidity. Sourcing sufficient Birr to purchase gold. Third, infrastructure. Lacking in-house assaying and secure vaulting.”
Without these capacities, banks could struggle to manage price volatility and operational risks.
Tujane noted that while commercial banks’ participation could enhance competitiveness, he doubted all could handle it.
“Some banks might manage, but not all. The transaction costs currently incurred by the central bank are very high. In this fiscal quarter alone, our region supplied about 4,158 kg of gold. That is a significant volume, and I think the possibility of all private banks managing this is low,” he told The Reporter Magazine.
To mitigate transition shocks, Eshetu recommends phased implementation.
“Gold bullion–licensed banks must turn to twinning arrangements with known players for at least 12–18 months,” he argued. Licensing should prioritize “capital-strong banks with at least 10–15 billion,” while the NBE should arrange emergency liquidity facilities to avoid credit squeezes, according to the banker.
He also sees a role for institutional coordination.
“Centralizing infrastructure at the ECX will help in meeting the December deadline,” Eshetu told The Reporter Magazine, describing the Ethiopian Commodity Exchange as “the best transitioning agent” for settlement systems and liquidity support.
The Reserve Question
Gold has served as a stabilizing reserve asset during periods of constrained external financing. A full exit from direct purchases raises legitimate questions about reserve accumulation.
The IMF review notes that the exit strategy must safeguard reserve adequacy and manage balance sheet risks.
Eshetu acknowledges that “the pace of direct reserve accumulation may slow as private banks build their own positions.” However, he argues that the NBE can shift toward purchasing refined gold in secondary markets rather than directly injecting liquidity into the domestic economy.
The shift is unfolding against a relatively supportive external outlook. IMF projections suggest gold exports could reach about 30 metric tons in 2025/26, while foreign exchange reserves are expected to rise to roughly USD 10.5 billion by the end of the program, covering around three and a half months of imports.
Eshetu also said a market-driven system using modern settlement infrastructure could improve the accuracy of external statistics.
“A private, market-driven system, especially one using a modern bullion platform with real-time T+1 settlement, will align financial flows with physical trade more closely, leading to more accurate and timely BOP reporting,” he said.
Regional Livelihoods and Market Discipline
For artisanal miners and gold-producing regions, the removal of the 15 percent premium may introduce uncertainty. The premium served as a predictable incentive.
Yet if exchange rates better reflect market conditions, the Birr value of gold could remain attractive even without a premium.
Tujane expressed concern that the removal of the premium might push gold back into smuggling channels.
“Personally, I’m afraid that may happen. Even now, some buyers in our region pay up to 27,000 Birr per kilogram, even though the central bank buys between 21,000 and 22,000 Birr. The premium especially for supplies over 10 kilograms compensates for that difference. But with the global gold price rising, some buyers may offer even higher, around 28,000 Birr, which could worsen smuggling risks,” he told The Reporter Magazine.
“The key is to ensure the formal market is efficient,” Eshetu cautioned. “Otherwise, producers may revert to the parallel market if transaction costs are too high or payments are delayed.”
Competition among banks could drive faster settlement and better service. But regulatory oversight will be critical to prevent fragmentation and abuse.
Tujane said he could not comment on how royalties collected by the region might be affected.
“Since the new modality hasn’t been communicated to us yet, I cannot say for sure. Previously, we had an agreement with the central bank, and royalties were collected based on the amount supplied. I don’t know if the private sector will follow a similar arrangement with the regional bureau. Until the details are clear, I cannot comment.”
A Structural Benchmark
Unlike discretionary policy adjustments, this reform is embedded within IMF program commitments. Authorities have pledged to develop a long-term exit strategy by December 2026.
If implemented effectively, Eshetu said the transition would “eliminate a significant source of monetary instability, create new opportunities for the private sector, and enhance the transparency and efficiency of the precious metals market.”
The shift represents more than an administrative change. It signals a broader realignment in Ethiopia’s economic governance, with the central bank stepping back from commercial operations to focus on its core mandate while private institutions assume a greater role in commodity markets.
Whether the transition proceeds smoothly will depend on sequencing, regulatory clarity, and institutional capacity.
But one conclusion is clear. Ethiopia’s gold will continue to flow. The question is no longer whether it should strengthen reserves or support livelihoods, but who manages that flow, under what rules, and at what macroeconomic cost.
Over the coming years, the answer may shape not only the gold sector, but the credibility of Ethiopia’s broader reform program.