
July 29, 2024 was far from an ordinary day for Ethiopia’s financial sector. The country awoke to news of a bold move by the National Bank of Ethiopia (NBE) to float the Birr. Although the move was not unanticipated, hinted at in the “homegrown” economic reform policy backed by the IMF and World Bank, it took many by surprise.
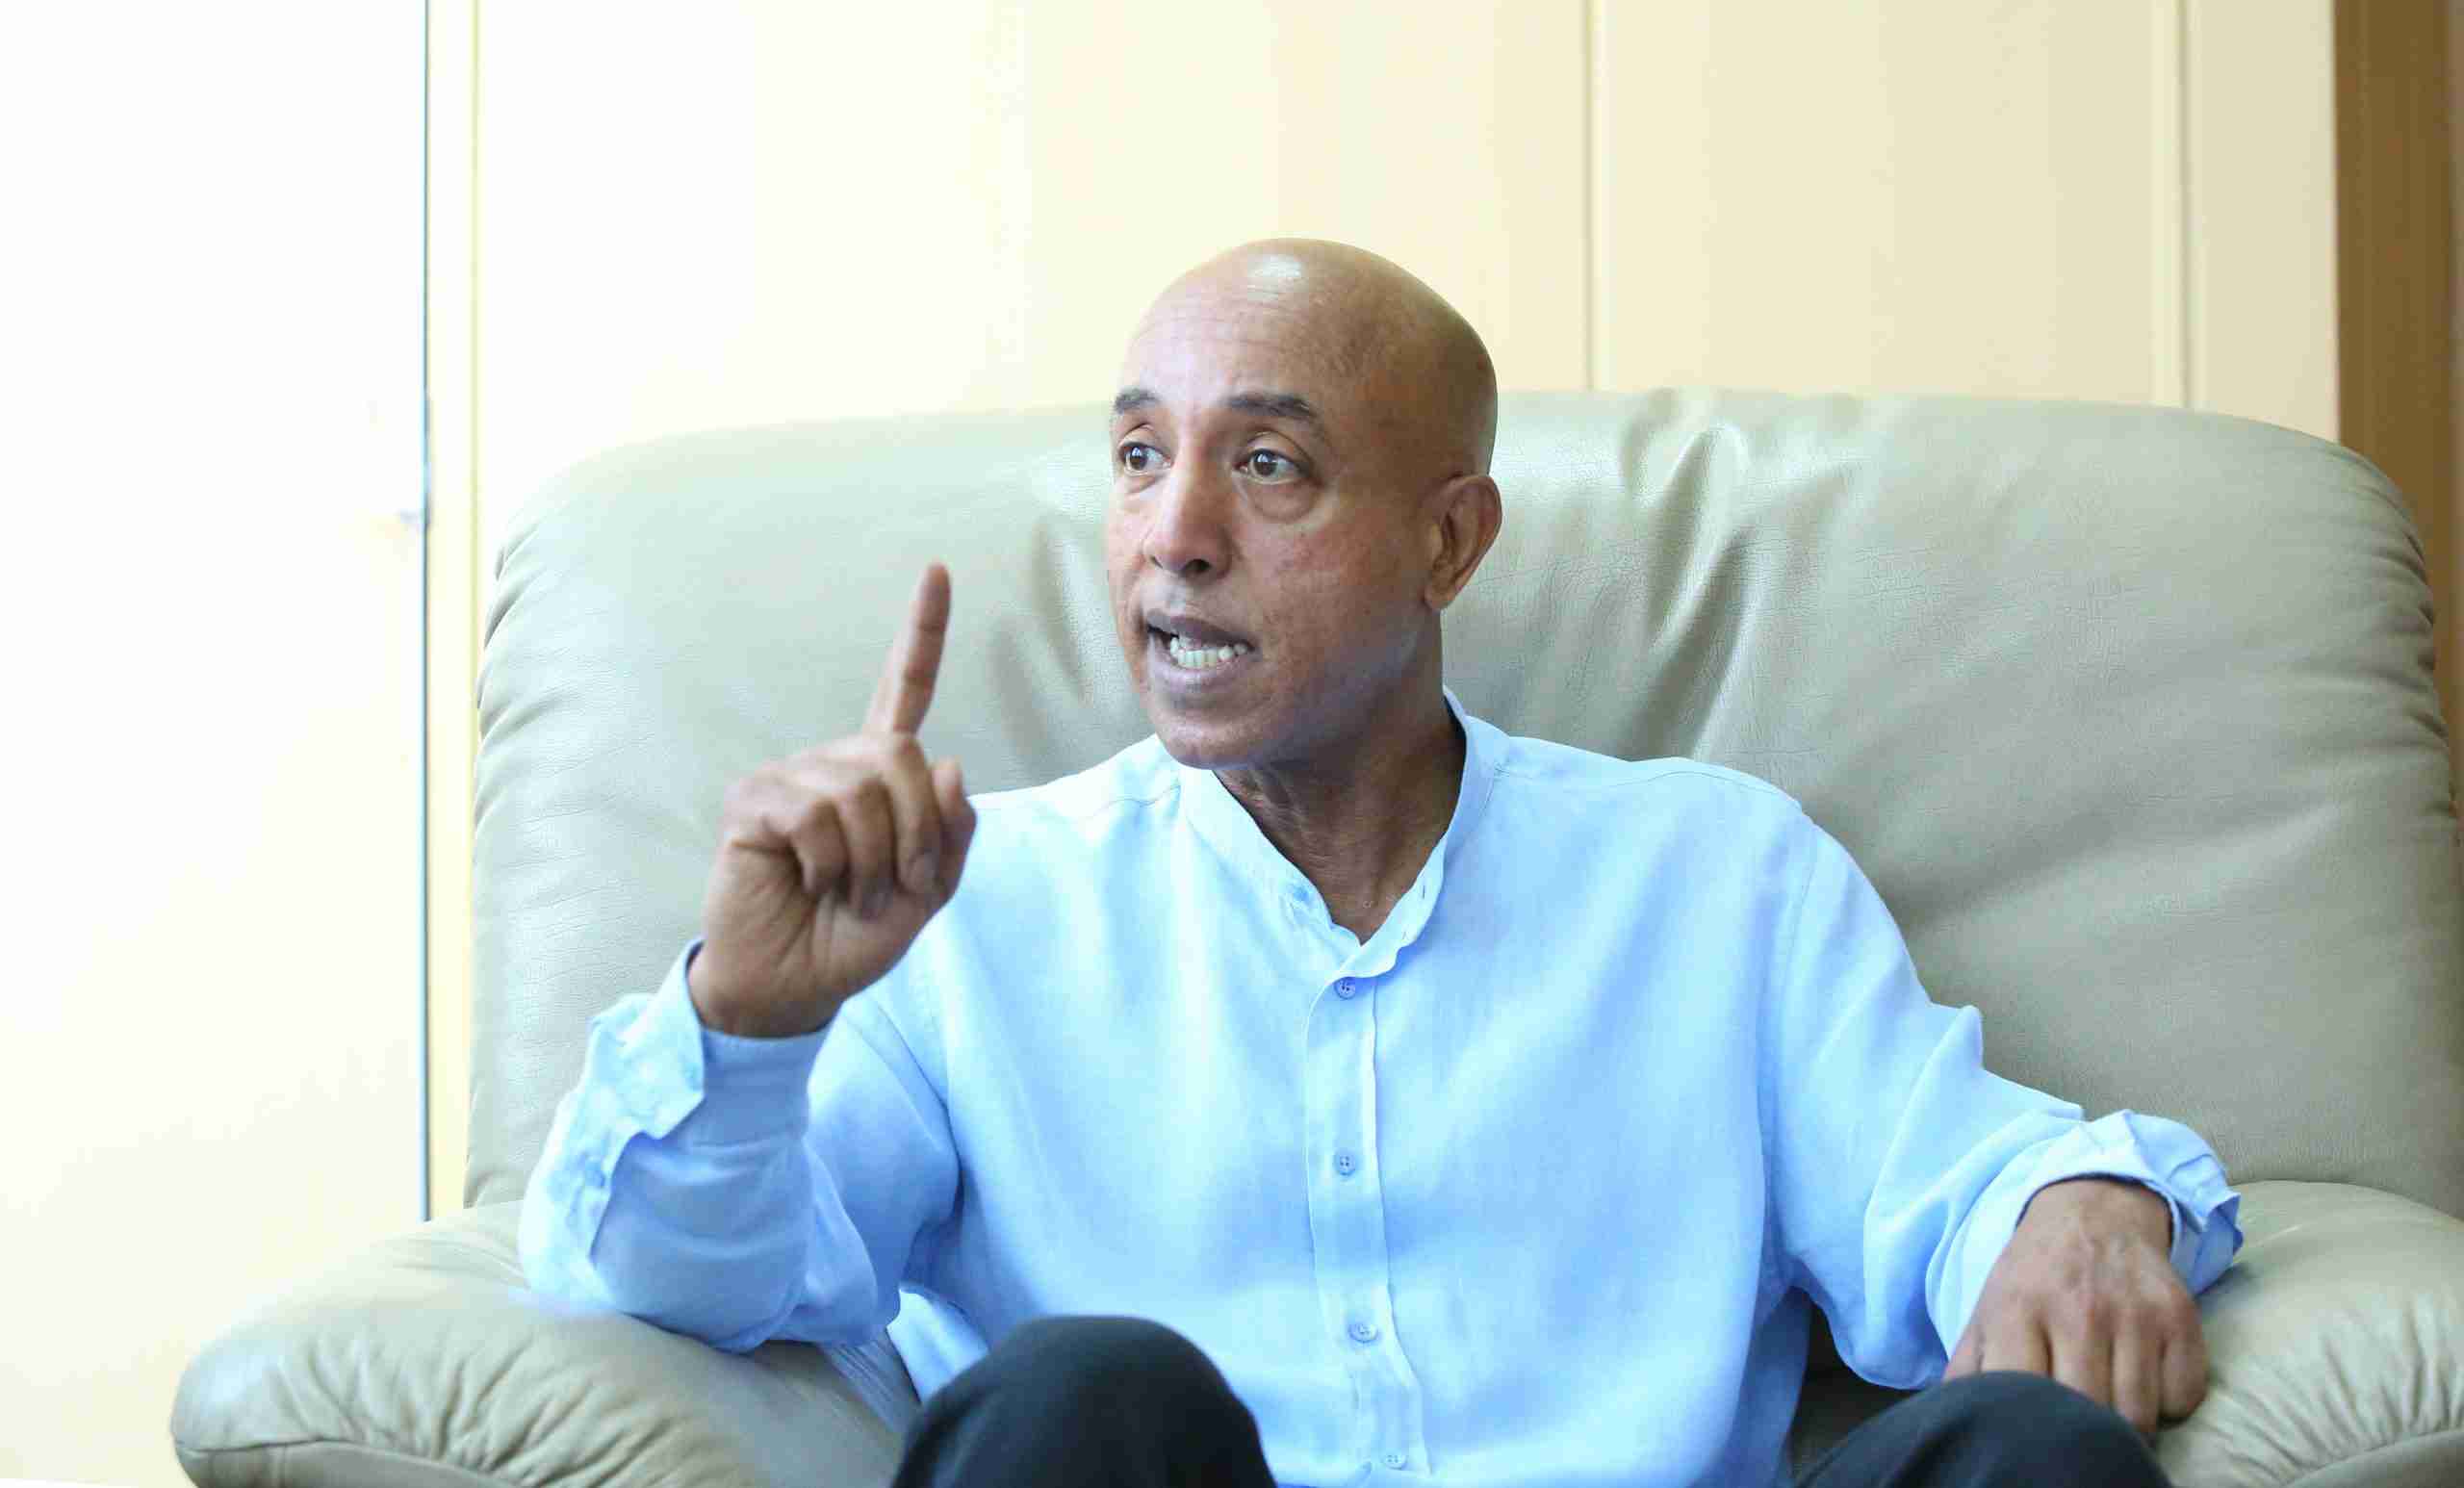
Governor Mamo Esmelealem Mihretu’s announcement sent shockwaves through the nation and confusion reigned, with many, including banks, hesitating to act. Some economists argued bitterly against the policy, warning of dire consequences. Yet, amidst this uncertainty, a few voices contended it was the best option available, even highlighting its potential benefits. Among these proponents was the controversial former Wall Street man and real estate pioneer Ermias Amelga.
Nearly a year into its implementation, the conversation has shifted from predictions to practical experience. So, what has truly transpired during this year-long journey? The Reporter Magazine’s Bewket Abebe caught up with Ermias Amelga to discuss just that. EXCERPTS:
RELATED POSTS
The Reporter Magazine: Eleven months ago, in the initial weeks after the NBE announced the bold move to float the currency, many were confused, and some economists warned it could end in disaster. At the time, you publicly offered an optimistic outlook on the new policy. After nearly a year, do you still hold the same stance, or have your views shifted?
Ermias Amelga: No, my stance remains unchanged. The situation necessitated this policy, and floating the currency was the only effective option we had. I’m certain of that.
Consider the gap between the official and black foreign exchange markets for instance. The rate has reached 150 Birr in the black market, up from 120 Birr. Without this policy, it might have skyrocketed to 200 Birr.

Some economists argued for a preparatory period before the currency float, suggesting an alternative: devalue first, allow some time, then proceed with the float. With nearly a year of practical experience, what is your view on this alternative argument now?
Implementing such an alternative would not have effectively minimized the disparity between the black market and official exchange rates. It is plausible the black-market premium could have escalated even more.
It is like being prescribed four pills a day to get better, but only taking one; it will in no way cure you. Worse, it could allow the disease to develop resistance, making your situation more dire. That alternative simply wouldn’t have been helpful.
So, there’s no question the policy needed to be introduced when it was; it was truly the reasonable path forward. The real challenge, though, is its implementation. Even the soundest policy is only effective if it’s properly put into action.
Do you believe this policy lacked proper implementation, and if so, what specific areas do you observe as being problematic?
For this policy to truly succeed, adequate supply of foreign currency is essential—a point I’ve consistently emphasized. Has there been enough foreign currency available? That is the question.
Following the announcement of currency floating, there was an expectation among many people that foreign currency would be readily available for them the very next day. However, this immediate access did not materialize. Although inflows from coffee, gold, and other sources did eventually contribute, this happened over a period, not instantaneously, particularly in the initial stages. The NBE later responded to the situation by introducing foreign currency auctions, though whether these provided adequate supply remains debatable.
Secondly, it’s crucial to remember that foreign currency isn’t a silver bullet for our economy. Ethiopia faces numerous other challenges that demand multifaceted approaches. Inflation stands out as a critical problem, inherently linked to devaluation—indeed, these often move in tandem.
In its attempt to curb inflation, the government has been compelled to tighten the supply of Birr through contractionary fiscal and monetary policies. This is where the core problem emerges: it can lead to stagflation—a combination of low economic growth and high inflation. This is arguably the most challenging scenario an economy can face, creating a significant dilemma. Addressing low growth typically requires loose monetary and fiscal policies, yet tackling inflation demands the exact opposite. Finding a delicate balance here is essential, as there’s no simple “black and white” solution.

Has the Ethiopian economy experienced stagflation over the past 11 months?
Yes, it has.
Considering the reported decrease in inflation and a projected GDP growth of up to 6.2 percent, how does this data (assuming its accuracy) strengthen the case for stagflation?
Alright, accepting the reported 15 percent inflation figure and the target of 10 percent, it’s clear the government remains committed to its anti-inflationary policies. The key point here is to closely monitor the impacts of these measures on the broader economy.
Maintaining balance remains critical. It is like aiming at a moving target: both underdose and overdose are harmful, as they either fail to fix the problem or create new, severe complications.
Which scenario best describes the current state: an overdose that harms, or an underdose that offers no relief?
I cannot offer a definitive answer without a thorough, in-depth look at all the detailed data. The NBE has implemented various directives over time, including efforts towards liberalization. To draw a reliable conclusion, we need to carefully assess the true impact of all these initiatives. Therefore, I prefer not to make speculative comments.
Looking back, what has actually transpired? Which specific sectors or groups have benefited from this policy, and which have experienced losses?
The economic situation is in constant flux. We have transitioned from an environment where currency and interest rates were primarily policy-driven to one governed by science of the market, and these two are fundamentally different.
A crucial element of market science is psychology. If people anticipate rising inflation, they’ll instinctively buy more now. Similarly, if merchants expect price hikes, they’ll hoard goods, creating a self-fulfilling cycle. This means market behavior is highly susceptible to expectations and even rumors. Such a system is challenging to navigate even for global experts. Even on Wall Street, with all its top market analysts, predicting precise market movements remains notoriously difficult. We are, without a doubt, facing a highly intricate economic management challenge.
This situation isn’t a painless remedy. Some benefit, others are barely affected, and many lose significantly. It’s like chemotherapy: a treatment meant to combat a serious illness, but it doesn’t distinguish between healthy and cancerous cells; its effects are indiscriminate. The process itself is inherently painful, impacting everything without distinction, much like it doesn’t selectively target just red or white blood cells. If your income is in Birr and you consume imported goods, you’ll be particularly hard hit. However, if you’re an exporter, this is akin to winning the lottery.

Has the measure truly helped exports perform better?
The policy’s effects aren’t uniform; they differ considerably across sectors. Some feel the impact swiftly, while for others, it’s a gradual, long-term unfolding. We observed an immediate surge in remittance inflows, for instance, demonstrating quick gains in certain areas.
However, if individuals or businesses decide to capitalize on this by entering, say, the export manufacturing sector, the benefits won’t appear overnight. Establishing such operations, from licensing to production, typically spans two to five years. This means the full realization of the policy’s benefits in these areas is a long-term prospect.
Overall, the situation is a complex tapestry. Every part of the economy appears influenced, with each experiencing distinct types and degrees of impact. The crucial task is to continuously adapt policy based on a close observation of these evolving trends.
Which areas do you believe would have seen better outcomes with more effective implementation, and which would have suffered substantial detriment had it not been enacted?
This is quite subjective. Could things have been worse without it? Absolutely, though I can’t quantify by how much. Could we have achieved better results with perfect implementation? Yes, but again, the extent is hard to measure. This requires a detailed examination of every aspect and all relevant data to draw a conclusive picture. I am hesitant to offer random estimates and create a misleading impression.
You might question why we haven’t made greater strides, but it is important to remember we have avoided falling off a cliff. We have been spared from that, at the very least. This is not to say we are without problems—we certainly are—but I believe the policy decision saved us from a far worse outcome. The key takeaway is that the situation remains complex and cloudy.
Right now, the more pressing concern isn’t a lack of foreign currency, but a shortage of the Birr itself. The tight monetary and fiscal policies implemented to curb inflation have severely strained liquidity. For instance, a factory with one billion Birr in working capital, intended for raw material imports, now finds that money’s purchasing power slashed by half. This halving of working capital impacts the entire economic system, underscoring the critical need for a sensitive balance in policy.
How severe do you perceive the current liquidity crunch to be for banks in Ethiopia?
I cannot offer a precise assessment as I don’t have access to the specific, detailed data required to comment definitively on current liquidity levels within the banking sector. I’m not in a position to comment on it at this time.
At the time, you strongly advocated for the currency float, arguing it would attract investment. Looking back, do you believe that claim about attracting significant investment has materialized?
While challenges with foreign currency repatriation were a considerable deterrent for investors, often causing years of delay and leading them to seek opportunities elsewhere, it’s crucial to recognize this isn’t the only factor at play. This successfully answered one of the primary questions investors would ask. However, it is important to note that this single improvement doesn’t guarantee investment.
Investment decisions are multifaceted. Above all, peace and security remain the most critical consideration. Investment, by its nature, shies away from instability; it cannot be enticed into an insecure environment, regardless of the incentives offered. The current climate is such that even domestic investors are hesitant to commit, let alone their foreign counterparts.