
The African Development Bank (AfDB), the continent’s largest multilateral lender, is poised to elect its ninth president today, May 29 in Abidjan, Côte d’Ivoire.
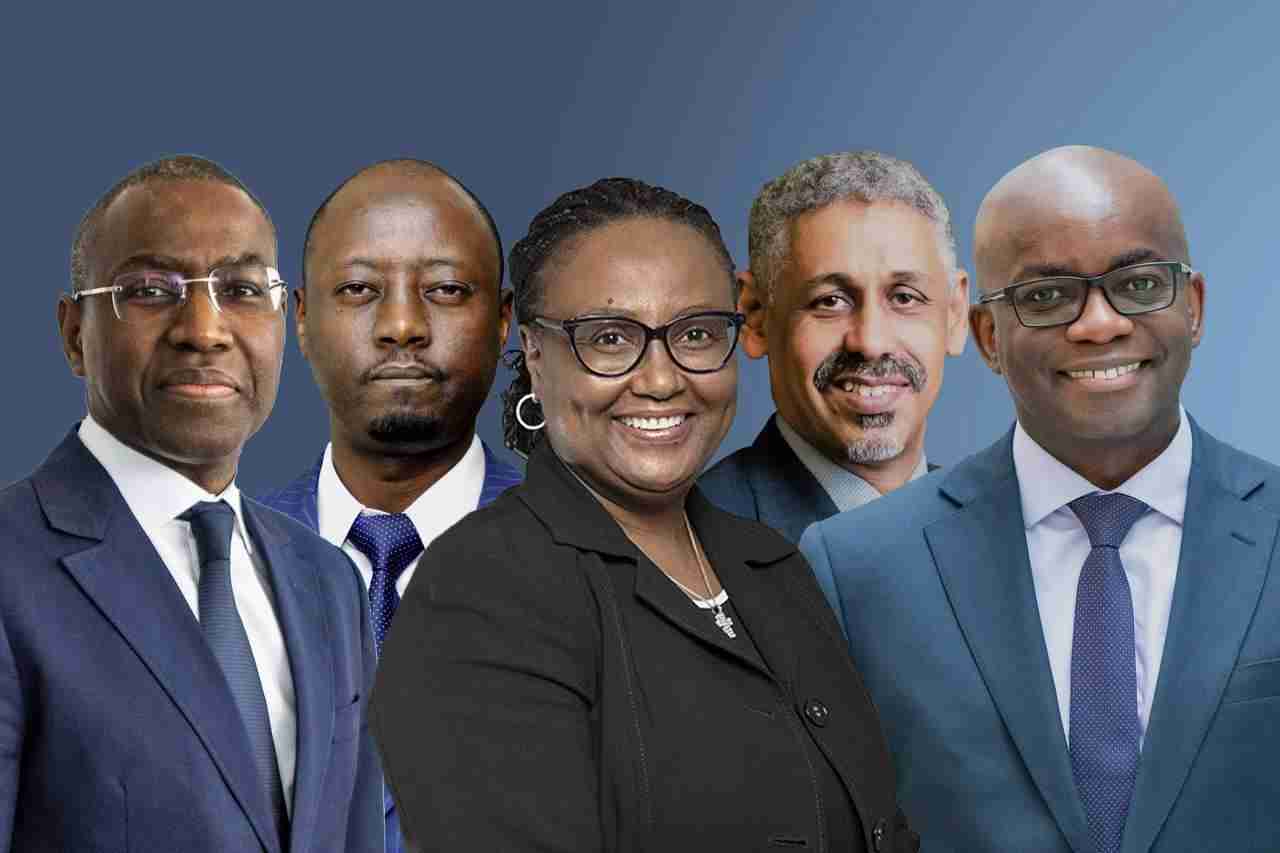
With five candidates in the race, the election will determine the leadership of Africa’s premier development finance body just as it faces an unprecedented financial challenge.
A proposed USD 555 million funding cut by the United States, announced earlier this month by president Trump, is believed to significantly impact the African Development Fund, the Bank’s concessional lending arm that supports low-income countries.
RELATED POSTS
Established in 1964 by the Organization of African Unity as the continent’s development financing institution, the AfDB now comprises 81 member states, including 27 non-African countries such as G7 members.
During this critical time of funding crisis, five candidates from across the continent are vying to lead an institution whose credibility rests on long-term development financing—particularly for projects deemed too risky by private capital.
The winner must secure at least 50.01 percent of the votes from the Bank’s 54 regional member states.
With an authorized capital of USD 318 billion and 81 member states, the AfDB has historically played a crucial role in infrastructure financing, climate resilience, and regional integration. However, its very funding model is now being tested.
Among the candidates, South Africa’s Swazi Tshabalala, a former senior vice president at the Bank, argues for tighter project selection and expedited delivery. She emphasizes, in an interview Bloomberg, that solving Africa’s infrastructure gap is foundational—and that partnerships with non-regional donors like Japan and Germany are key to sustaining momentum.
Senegal’s Amadou Hott, a former economy minister and special envoy for green infrastructure, believes Africa must unlock its own capital—an estimated USD4.5 trillion in assets held by individuals, pension funds, and insurers. Hott told Bloomberg that real progress depends on financial sovereignty and the creation of an African credit rating agency to improve borrowing terms.
Zambian candidate Samuel Maimbo, a World Bank vice president with endorsements from SADC and COMESA, brings experience in global fundraising. In response to the U.S. funding threat, he sees an opportunity to reengage Washington diplomatically, warning that the proposed cut is a “wake-up call” with potentially devastating consequences.
Mauritania’s Sidi Ould Tah, formerly head of the Arab Bank for Economic Development in Africa, leans toward Gulf nations for alternative funding. He told Bloomberg that Africa hasn’t fully tapped Middle Eastern liquidity and that climate resilience must become central to the Bank’s agenda.
Abbas Mahamat Tolli of Chad, ex-governor of the Bank of Central African States, underscores the urgency of attracting private investment to bridge Africa’s USD150 billion infrastructure shortfall, as he told Tchadinfos the Chadian news site.
The winner of this election will inherit an institution at a crossroads. As Africa grapples with debt, climate change, and diminishing Western aid, the next AfDB president must not only stabilize finances—but also redefine the continent’s development path in a rapidly evolving global order.