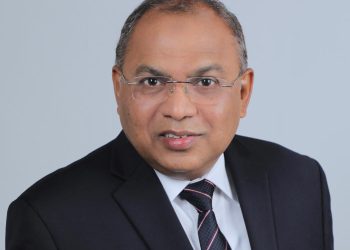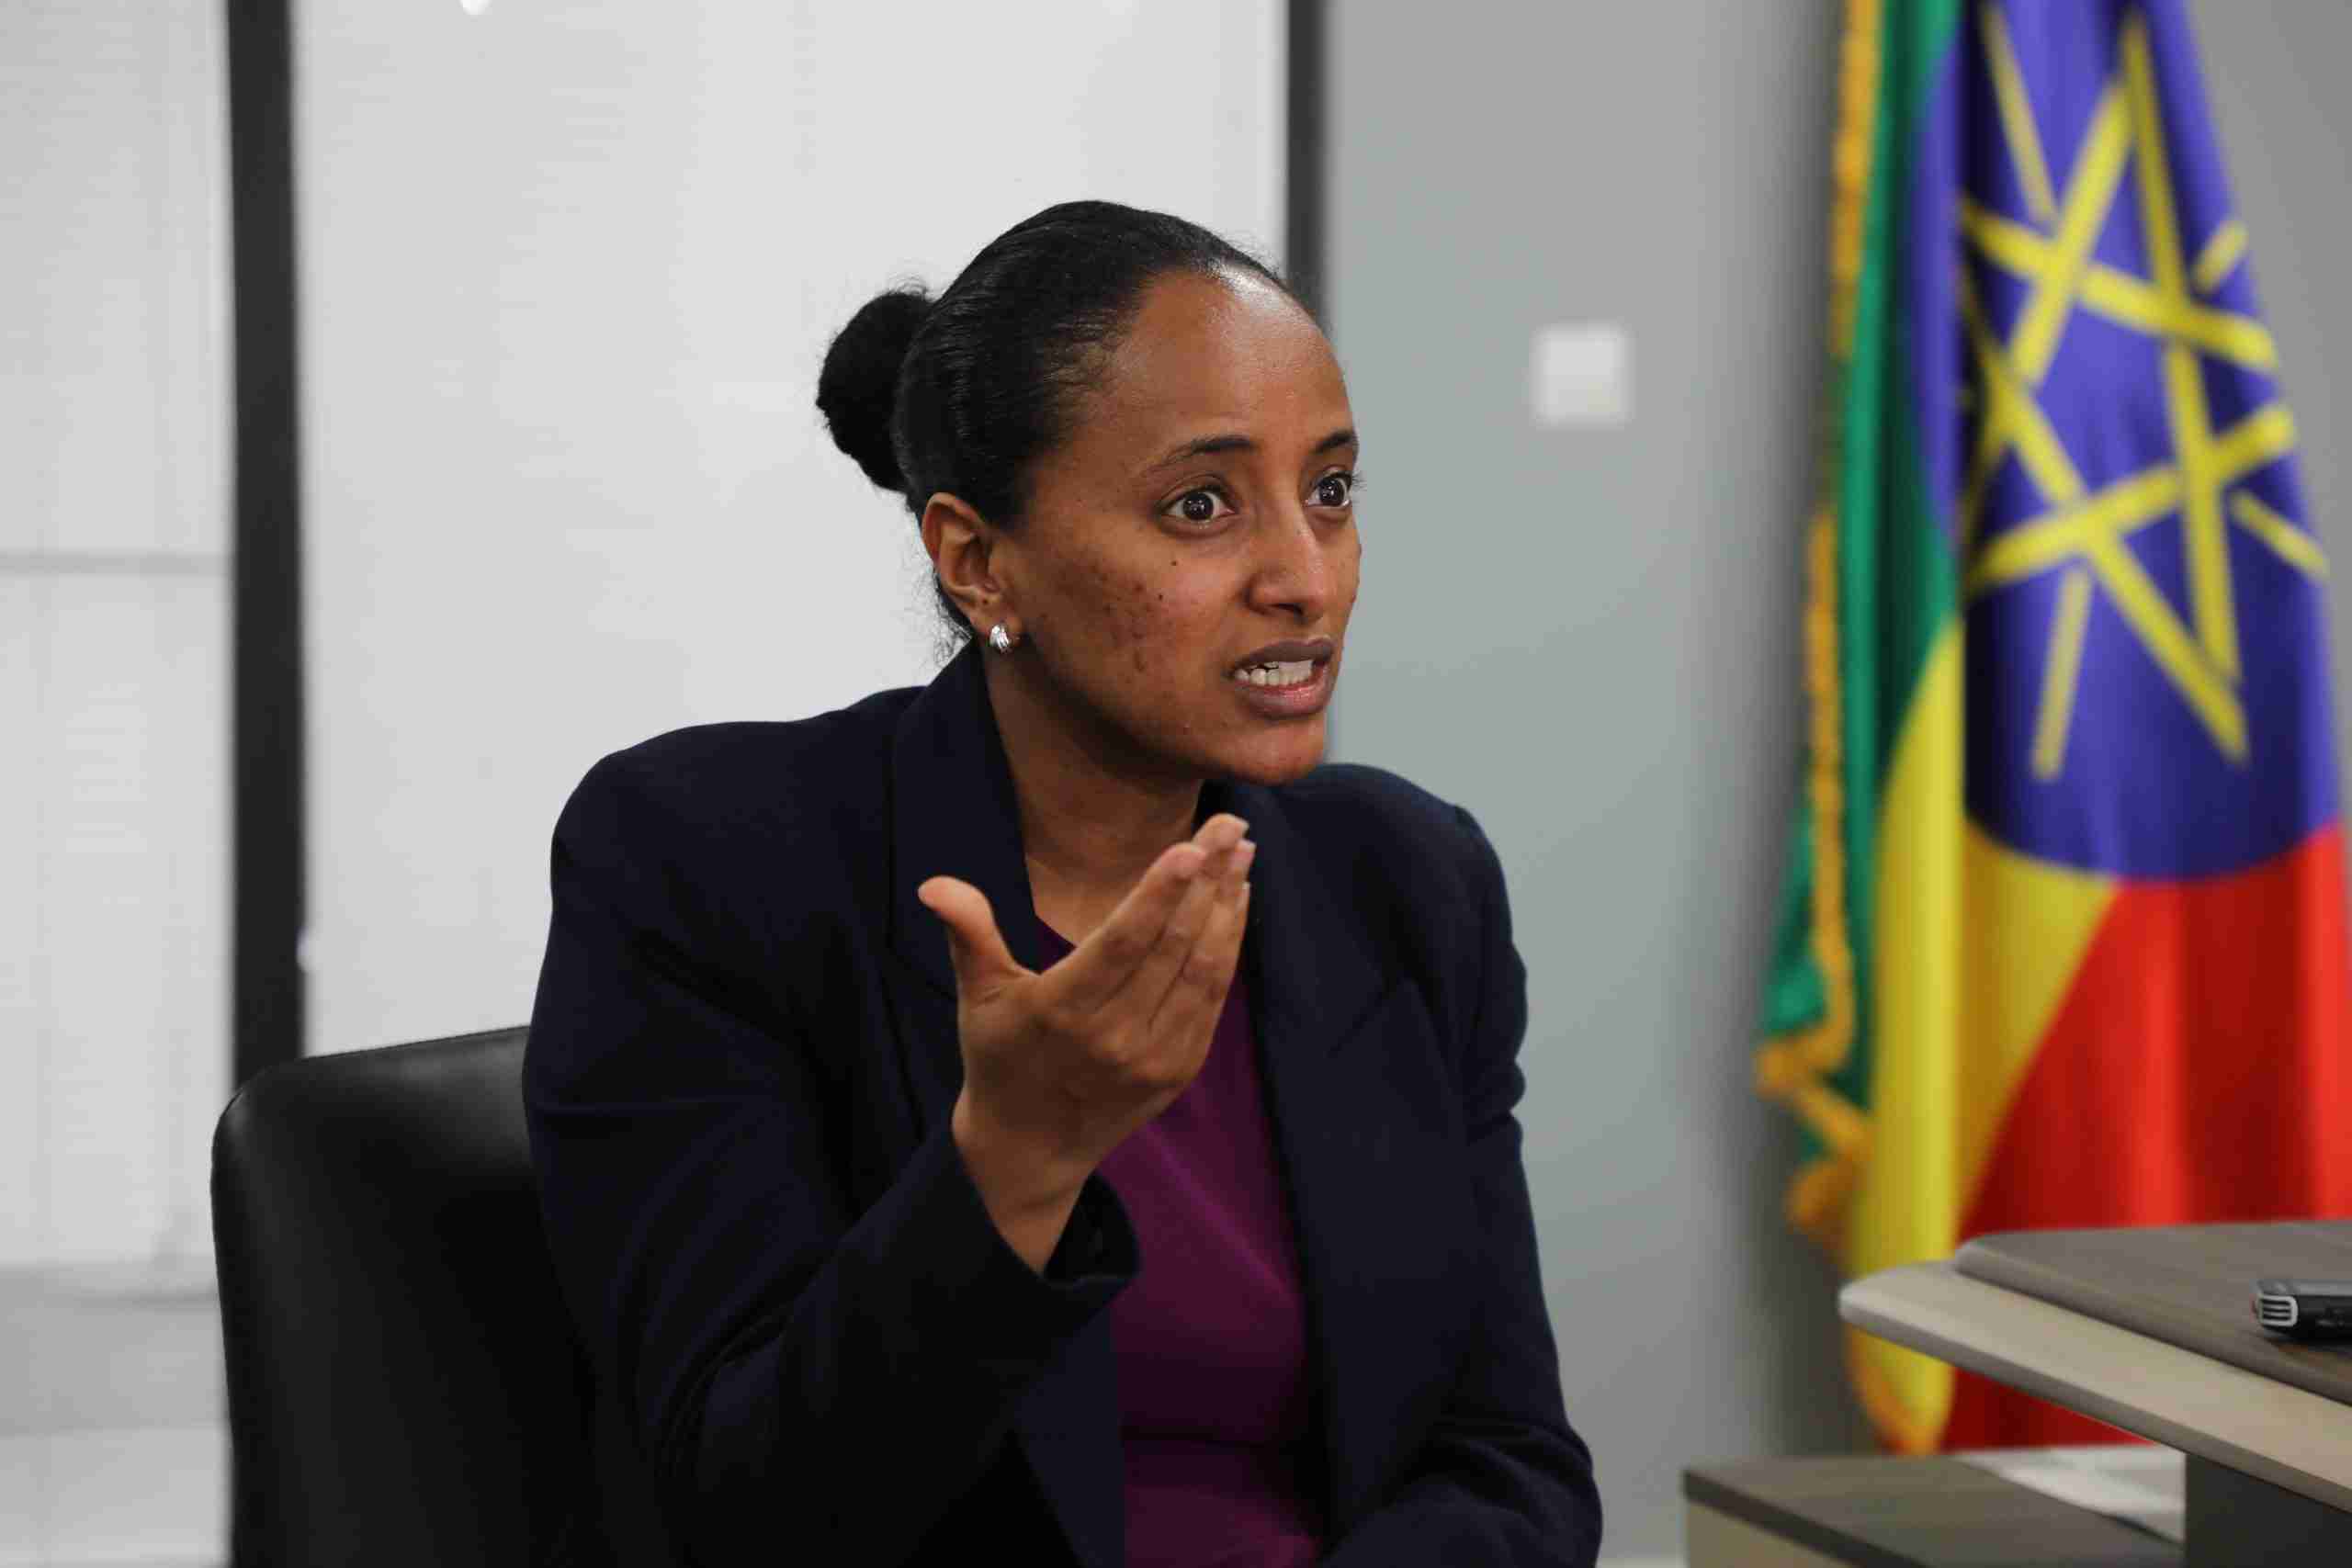

After a hiatus lasting longer than half a century, Ethiopia has reintroduced a capital market as part of the economic reforms being undertaken by the current administration. The Ethiopian Securities Exchange (ESX) was launched in the first few days of 2025, under the watchful eye of Hana Tehelku, who heads the Ethiopian Capital Market Authority (ECMA).
The Authority itself, which is charged with ensuring market integrity, fairness, and accountability, was established in June 2021, with Brook Taye (PhD) serving as its founding Director-General. He is largely credited for laying the groundwork for ECMA’s legal and operational frameworks.
In August 2024, a few months before the highly anticipated launch of the ESX, Hana succeeded Brook at the helm of the Authority. With training in law from Mekelle and Addis Ababa universities and in Community Development and Theology from EGST (a Protestant theological school), Hana’s prior experience includes roles at the Ministry of Justice and the former Revenue and Customs Authority, where she focused mainly on addressing economic crimes.
RELATED POSTS
The Reporter’s Yared Nigussie sat down with the Director-General for an inside look at what goes on behind the scenes at ECMA and its plans for the future of securities trading in Ethiopia. EXCERPTS:
The Reporter Magazine: ECMA recently announced the pilot phase of an initial public offering (IPO) clinic. Could you explain what an IPO clinic is?
Hana Tehelku: An IPO clinic serves as a platform where companies—referred to as issuers—can share their experiences and insights as they prepare to issue shares to raise capital. This capital helps businesses expand, pay expenses, and increase their profitability, using shareholder investments to grow. However, in many African capital markets, there’s a significant gap in IPO activity. This lack of IPOs directly impacts market liquidity and hinders the broader use of capital markets for raising funds. It also limits investor participation, both from retail and institutional investors.
In Ethiopia, for instance, we have seen existing companies engaging in buying and selling shares without the presence of a formal regulatory authority. Our goal at ECMA is to help these companies transition into a more structured capital market. By doing so, we aim to introduce new companies, new shareholders, and more opportunities for raising funds, especially from the public. In this regard, the IPO Clinic is designed to make it easier for share companies to access the capital market at the national level. Since the introduction of the Ethiopian Capital Market Authority (ECMA), along with its regulations, we now have a framework for how companies can raise capital from the public.
Rather than simply telling the market what to do, our goal is to show companies how to do it by providing guidance and showcasing successful examples of companies that have successfully raised funds from the public—outside of the financial sector, such as banks and insurance companies.
The scope of the IPO Clinic is multifaceted. It helps existing companies bring their shares to the market, offering liquidity for service providers like brokers, investment banks, and the Ethiopian Securities Exchange (ESX) itself. In addition, it supports companies outside of the banking and financial sectors who are looking to raise funds. The clinic is supported by the World Bank, which has provided a consultant to assist in the design of the clinic. The first step in this process was to develop the clinic’s framework, which includes defining the services it will provide, identifying the necessary staff and resources, and determining how we can best support the market as companies come through the IPO process.

What kind of support are you receiving from the World Bank? And how much funding have you secured?
Support from development partners like the World Bank usually comes in various forms. For us, the primary form of support has been technical assistance. The World Bank has been instrumental in providing advice, offering technical expertise, and introducing concepts to the market that are crucial for the success of the IPO Clinic. While the World Bank does not directly provide financial funding to ECMA, they have hired a consultant to help with the design of the IPO Clinic. This consultant’s role includes developing the clinic’s framework and facilitating demonstrative transactions for two companies. These companies will serve as success stories, showcasing the IPO process and highlighting the potential of Ethiopia’s capital market. The technical support from the World Bank has been continuous and invaluable.
They have been actively involved throughout the entire process, including participating in the steering committee and providing essential feedback on the draft design document for the IPO clinic. Additionally, the World Bank has shared its vast experience from capital markets in different jurisdictions, which has been crucial. Their insights and expertise have been integrated into the clinic’s design documents, ensuring that we’re on the right track to create a robust and effective IPO process. We’ve already signed on the draft design of the IPO clinic, which was reviewed by the World Bank. They have provided excellent insight into the IPO design document.
In February, you published a public notice asking publicly held companies with 50 or more stakeholders to submit details about their companies. Why is this necessary?
One of the most crucial regulatory frameworks introduced by ECMA is the Public Offering and Trading of Securities Directive number 1030/2024. This directive requires public companies to register their securities with ECMA, a step that’s vital for ensuring proper oversight and transparency in our capital markets. The directive divides companies into two categories: those that started their offerings before the directive’s enactment in November 2024, and those that began their offerings afterward.
For companies that started their offers after November 2024, the requirements are clear: they must secure the services of a transaction advisor, obtain a legal opinion, and hire an external auditor to carry out their offer. Additionally, they must register their prospectus with ECMA before offering their shares to the public. There are no exceptions to this rule. Any company offering securities to the public after November 2024 must register those securities with ECMA before proceeding with their public offerings. However, companies that began their offers before the directive was introduced are given a one-year window to conclude their offerings, prepare the necessary documents, and register their securities with ECMA by November 2025. To effectively implement this directive, ECMA needs to be notified of any ongoing or upcoming share offerings by publicly held companies. This notification serves as a tool for ECMA to assess how the public offering directive should apply to existing and new offers. In essence, the public notice serves as a regulatory tool, allowing ECMA to gather crucial information about publicly held companies and track their offerings. ECMA, as a regulator, should have to have enough information to regulate the market.
We’ve been in regular contact with the Ministry of Trade and Regional Integration, as well as the Documents Authentication and Registration Service (DARS), to gather data about existing shareholders. However, it’s important for us to hear directly from the issuers themselves. This public notice serves as a way to initiate direct communication with companies, ensuring they understand their responsibilities and the opportunities the capital market offers.
This process also functions as a data consortium, giving ECMA a clearer picture of the market. It’s an entry point for us to begin conversations with issuers, helping them navigate their responsibilities and understand the regulatory environment. Most companies have already provided their data, and we are grateful for their cooperation. This information will be invaluable not only as a source of regulatory data but also as a tool for facilitating ongoing communication between publicly held companies and ECMA.

How does ECMA intend to balance regulatory oversight with fostering innovation around the financial products offered via ESX, such as derivatives or exchange-traded funds (ETFs), which might come later?
Balancing ECMA’s responsibilities for market development vis-à-vis regulation—especially when it comes to investor protection and reducing systemic risk—is a challenging task. It’s akin to performing in a circus, where you’re standing on a thin wire. While it’s incredibly difficult, it’s a necessary part of the job. Just like a circus performer must master their craft, we must successfully navigate the delicate balance between regulation and innovation.
I have to admit, it’s no easy feat. Achieving this requires meticulous planning and careful execution. The process of designing regulations and driving market development has to be done with great attention to detail, ensuring that one responsibility doesn’t undermine the other. For example, market development efforts shouldn’t send a message to the market that ECMA is willing to compromise its regulatory duties. Whether it’s market supervision or enforcement, we have to be clear that regulation and growth can coexist without one side weakening the other.
A good example of how we’re working to strike this balance is our initiatives, such as the sandbox. This is one of the unique ways we’ve approached the challenge of harmonizing our regulatory powers with market development. While it’s not easy, we’re navigating these tasks carefully, always mindful of the broader context.
When developing our regulatory frameworks, we make it a point to study the approaches of other jurisdictions. However, we also remain keenly aware of Ethiopia’s specific needs and context. Our ongoing discussions at ECMA are centered on ensuring that our regulations accommodate Ethiopia’s unique market environment. It’s been a valuable learning experience, and we continue to adapt and refine our approach based on what we’ve learned from this process.
What role do you foresee ECMA playing in developing secondary markets alongside primary issuances once ESX becomes more mature?
To understand ECMA’s role in developing secondary markets alongside primary issuances, it’s important to look at the major components of the market. In both the primary and secondary markets, issuers offer their securities to the public. This can include existing banks, insurance companies, or companies in sectors such as manufacturing, real estate, and logistics.
We should make sure that existing companies are coming to the market, either they trade on the exchange or the over-the-counter (OTC) market. We know the ESX has both licenses. To make sure all existing publicly held companies are coming to the market, you can see the public offering trading directive. All publicly held share companies should be registered at ECMA, even if it depends on when they are doing the offer.
Our goal is to ensure that existing companies are actively engaging with the market, either by trading on the exchange or in the OTC market. ESX holds licenses for both types of trading, which gives us flexibility. To bring these companies into the market, we look at the public offering trading directive, which says that all publicly held share companies must register their securities with ECMA, regardless of when they are planning to issue shares.
Once companies are registered with ECMA, they must trade through a licensed trading system, using intermediaries that are also licensed by ECMA. This ensures that the exchange has liquidity, which is essential for its maturity and growth.
Our regulatory frameworks are designed to ensure that securities and related documents maintain high quality, with the involvement of experts. We want to ensure that all share companies entering the market contribute to liquidity and support service providers.
In essence, our regulations are meant to protect everyone in the market: issuers, the exchange infrastructure like ESX, and service providers. ECMA isn’t just focused on regulation; we’re working to create a dynamic and sustainable market where everyone benefits from our frameworks. The aim is to keep the market rolling, ensuring that it evolves and matures for the benefit of all participants.

Looking ahead, what milestones does ECMA aim to achieve within its first year of launch concerning listings, trading volumes, or other key performance indicators?
Developing a capital market is not an overnight task. It’s not like turning on a tap where everything flows effortlessly; much of the infrastructure has to be built over time, and it can take anywhere from five to ten years. A lot of backstage work is needed to ensure that when people come to the market, they have what they need to succeed.
To measure the success of a capital market, we rely on a variety of key indicators. For example, the number of companies listed on the exchange and the trading volumes are obvious benchmarks. Equally important is the diversification of investor participation, whether it’s retail investors, institutional investors, or both. We also look at the range of products and services introduced to the market, beyond just equity and bonds. For instance, we could see the introduction of government bonds, or even Sharia-compliant products like Sukuk bonds.
One of our priorities as a regulator is ensuring that compliance becomes a valuable tool for both issuers and the broader market. By November 2025, we aim to have all existing companies register their securities with ECMA, and trade on the exchange using licensed service providers. This will be a significant milestone for us, as it will solidify the proper structure for capital market participation.
Additionally, we are working on a capital market master plan, which will serve as a roadmap for the next 10 years. We have already signed a Memorandum of Understanding (MoU) with Financial Sector Deepening (FSD) Africa, which will help us assess our current position and set clear goals for where we want to be over the next decade. From this 10-year master plan, we will develop a strategic plan for the next 3 to 5 years.
For now, our main objective is to establish ourselves as a regulator who ensures everyone has a clear understanding of the capital market regulations and is fully aligned with them. Embracing this regulatory framework will be a crucial step for us in the years ahead.
What strategies is ECMA considering to enhance cross-border trading capabilities and partnerships with other African stock exchanges, thereby boosting regional economic integration?
As a regulator of the Ethiopian market, ECMA’s role extends beyond just managing our own domestic market. One of our top priorities is integrating with the broader international community of regulators. We are actively working on fostering alignment with international organizations and regional entities that facilitate cross-border regulation. These collaborations help streamline the regulatory process, making it easier for one regulator to interact with another across different jurisdictions.
While I can’t provide a specific timeline for when this will be fully realized, I can assure you that strengthening these cross-border partnerships is a key focus for us. This collaboration will play a crucial role in enhancing the capabilities of our market and supporting regional economic integration across Africa.
How does ECMA plan to integrate fintech solutions to improve cross-border trading efficiency among African stock exchanges?
Since its establishment, ECMA has recognized and embraced the crucial role of technology in capital market development. For example, in our Capital Market Service Providers Licensing and Supervision Directive, we acknowledge service providers that rely on advanced technologies, such as robo-advisory Services and digital sub-broker services. These solutions utilize tools like Artificial Intelligence (AI) to offer capital market-related services more efficiently.
On the technology front, we’ve also invested in state-of-the-art systems for market supervision and Central Securities Depository (CSD) operations. These technologies are designed to enhance the efficiency and scalability of our market. In particular, they make it easier to integrate with other markets, whether regional or international. For instance, if we are looking to enable cross-listings, the advanced clearing technologies we’ve adopted will be key in facilitating smooth connections with regional exchanges, as well as with markets in Europe and the United States.
By leveraging such fintech solutions, we are not only enhancing the efficiency of our local market but also positioning ourselves for seamless integration into the global trading ecosystem.
The untapped potential of the African Continental Free Trade Area (AfCFTA) is seen as a significant driver for Ethiopia’s economic development. How does ECMA plan to align Ethiopia’s emerging stock market with the AfCFTA to attract cross-border investments and facilitate pan-African capital flows?
AfCFTA is focused on eliminating trade barriers, including tariffs, and ensuring the free movement of people and assets. Importantly, this also includes financial assets. By reducing these barriers, it becomes much easier for businesses to engage across borders, and that opens up opportunities for investments and capital flows throughout the continent.
For instance, Ethiopian companies shouldn’t be restricted to raising funds within Ethiopia alone. With the AfCFTA in place, an Ethiopian company could raise capital in neighboring countries like Kenya, Rwanda, or Tanzania. Take Rwanda’s capital market as an example: they consider East African retail investors as domestic investors for tax purposes and other incentives. This alignment in regulations allows Rwandan companies to raise funds not just in Rwanda, but also in Kenya and Tanzania with relative ease.
The goal is to make cross-border fundraising easier across the continent, reducing barriers for companies to raise capital in different jurisdictions and even engage in cross-listings. This would also promote the transfer of expertise, as the free movement of people would make it simpler for professionals to share their knowledge across borders. For example, if I wanted to travel to Kenya, I wouldn’t need a visa, and I could easily exchange expertise there — and vice versa.
This dynamic is highly beneficial for capital market development and will facilitate cross-listings, opening up opportunities for capital market providers in Ethiopia and across Africa. Ultimately, this will strengthen pan-African capital flows and foster more integrated financial markets.
Will ECMA adopt regulatory sandboxes to pilot financial products such as crypto-assets and derivatives while managing systemic risks?
When it comes to digital assets, the issue is largely a matter of government policy, as it’s a delicate subject. For example, if the discussion revolves around making cryptocurrencies legal tender, that falls under monetary policy and would be handled by the National Bank of Ethiopia, not ECMA. However, if we’re talking about the securitization of these assets, that definitely falls within ECMA’s regulatory bandwidth.
That said, a broader approach might be necessary. We may need a national digital asset policy to assess the advantages and disadvantages of recognizing digital assets as assets in Ethiopia, as well as to understand the risks they pose. This requires careful study and consideration.
Regarding crypto-assets specifically, we’re keenly aware of the regulatory challenges, as this is a two-way street. We’re not just regulating the market; we’re also learning from this exercise. If the ecosystem starts producing new products and services, ECMA must be proactive in understanding these developments, determining how to regulate them, and deciding whether we need to regulate such products at all.
If we choose to regulate these products, we’ll need a robust and flexible regulatory framework to accommodate a variety of financial products and services. Since we’re just starting out, our regulatory services might not yet be fully equipped to handle all the products the market might produce. We’re still in the early stages of developing that flexibility.
As for our first regulatory cohort, we’ve been fortunate to receive over 40 applicants, though not all fall within ECMA’s current regulatory framework. We’ve identified the ones that are within scope and are now in the final phase of testing these products and services. We’ll monitor the results carefully. After the first cohort, we plan to continue with more cohorts, but we want to ensure we’re learning the right lessons from the first round before proceeding further.
How will the Authority balance the desire to see foreign participation with safeguards to prevent potential volatility from speculative capital?
When Ethiopia opened its capital market, we made sure it was accessible to both domestic and foreign investors. However, simply having an open market isn’t enough; we also need a clear direction and a strong regulatory framework to manage foreign portfolio investment. As you rightly pointed out, foreign investors bring both benefits and risks.
To manage these risks, ECMA is actively working on a comprehensive foreign portfolio investment policy. We have a dedicated team focused on studying the potential benefits and challenges that foreign investment might bring to our market. Our goal is to understand how foreign investment can positively impact our economy while also addressing the risks, particularly the potential for volatility that comes with speculative capital entering and leaving the market.
We’ve been examining how various jurisdictions, including China, India, and Nigeria, have navigated these issues. We’ve looked at how they’ve benefited from foreign investment and how they’ve dealt with the challenges, especially in terms of mitigating market volatility. While we don’t plan to adopt all the strategies used by these countries, we aim to ensure that the measures we do adopt are tailored to our specific context, particularly considering the ongoing economic reforms in Ethiopia.
Ultimately, our goal is to strike a balance: we want to encourage both domestic and foreign retail investors while also ensuring the stability of our market. We are working carefully to adopt tools and mechanisms, commonly used by both African and Asian markets, to safeguard against the volatility associated with foreign capital flows.