

Among the foremost entities introduced to the Ethiopian institutional landscape during Prime Minister Abiy Ahmed’s (PhD) administration is the Ethiopian Investment Holdings (EIH), a giant but little-known agency created to manage the nation’s sovereign wealth.
EIH currently oversees a portfolio of 40 state-owned enterprises, including giants like Ethiopian Airlines, Ethio telecom, the Commercial Bank of Ethiopia, and Ethiopian Shipping and Logistics, effectively placing a substantial portion of the nation’s wealth under its management.
Initially led by the current Governor of the National Bank of Ethiopia, Mamo Esmelealem Mihretu, EIH is now helmed by Brook Taye (PhD). Both leaders are often associated with the ‘Chicago Boys’ group and its market-oriented economic views. However, in his new capacity, Brook says the government’s plan is to ‘reform SOEs, not privatize them.’
RELATED POSTS
Has there been a change of plans for public enterprises? Brook, who, in addition to his legacy in designing the capital market landscape in Ethiopia, is known by many for his work in privatization efforts during his capacity as an advisor to the Ministry of Finance in the early years of the administration. Today, he says the government’s earlier intent to sell off SOEs was just a ‘misunderstanding.’
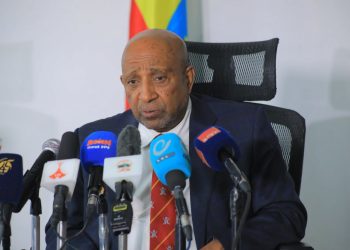
The Reporter Magazine’s Bewket Abebe caught up with the man steering the ship to see if there is a change of heart, what is going on behind the scenes at the nation’s first sovereign wealth fund, the details of a reform program for SOEs, and much more. EXCERPTS:
The Reporter Magazine: Between late August and early September, you conducted annual performance reviews, or ‘performance dialogues,’ with the state-owned enterprises (SOEs) under your purview. Could you share some insights about those performance reviews, including the process involved and the kind of data you receive(and how it differs from the data publicized?
Brook Taye (PhD): The performance dialogue was very important; one, for me to know our subsidiaries’ performance; their board performance, their strategies, their financial performances, and their CEOs’ performances. In this regard, it was an important platform and I really appreciate the momentous task they have. Second, the way we conduct performance reviews usually hinges on a couple of points. These entities share with us their financial performance and operational performances. Based on that report, we form an opinion and prepare a rating of these companies. The rating has several components: financial, operational, performance of board of directors, and corporate social responsibilities. We prepare a consolidated financial rating for this company considering these components.
Additionally, we undertake exhaustive interactions with the companies; their board and CEOs in order to capture the subtle information that we need to get. The performance dialogue was an excellent platform.
The data we receive is mostly financial and operational information. We are moving into a strategy whereby we will, unless it is confidential business information, make information about the enterprises available to the public.
Tell us more about how you determine the ratings.
We have three grades: Green, Yellow, and Red. Take finance, revenue growth, and cash conversion cycles for instance. How long does it take for a company to convert the cash it received, the revenue, into capital, into something that is profitable? We measure that. We measure the companies’ performances against our benchmarks, our KPI. Depending on that, we will have a consolidated view considering those components. We also consider the global situation. If shipping companies are growing by five percent and ours grows by four percent, we grade it yellow.
How many of your subsidiaries have you categorized as ‘Green’ and how many ‘Red’ in your most recent rating?
I don’t have the exact number in my head right now. But I can tell you the majority were rated green and yellow. We have a few companies rated red mainly due to their financial performance; the unavailability of clean audited financial reports. And we have on the other hand companies that have not been profitable, such as the Ethiopian Mineral Corporation. We are doing a turnaround; we had to change the CEO and the board composition. We hope it will be transformational. Financial performance remains the very critical first priority in our ratings.

Experts routinely criticize the tendency of some SOEs, even those many consider most profitable, to present overly optimistic performance narratives while the reality that lies in the details often tells a different story. In your observation, which aspects of SOE performance are most susceptible to misrepresentation?
The criticism is legitimate. I take that because it is based on [real] experience. The critics know people publishing public documents claiming that they farmed 10,000 hectares when no more than 100 hectares [was farmed]. Reporting using inflating revenue and profits are all past legacy problems we have inherited from our SOEs. So, the skepticism is legitimate. But as owners, at EIH, we have a much deeper understanding and ability to go through the reports, the numbers, the details, and what exactly is going on there. If you report you have generated a billion birr in revenue, I will be able to see it on your balance sheet. If you say your company is growing by ‘X’ percent this month, I can see your cash flow statement and be able to tell whether it is true. But in order to do all of that, the company has to be audited by an external auditor. All of our companies have an externally audited report for the 2015 E.C. fiscal year, and we are working on 2016.
Unless we receive a clean and qualified externally audited report, we don’t approve any requests for investment from a company. Similarly, when they need support like borrowing from a bank, we rely on those numbers. And of course, we have experts.
Let me share with you what we are doing with such cases right now without mentioning the names of the companies. There are companies whose information we are not satisfied with. What we have done is bring in three phenomenal external finance experts to do the entire review of financial flows for these companies. We deploy them to the headquarters of these companies. We make sure they have access to all the data. They are aggressively identifying all the issues. If there are any misappropriations, we will know it. If this is something to do with mismanagement, we will correct it. If it has to do with anything crime, we will be able to take action through the appropriate government agencies.
We are very aggressive. We take this very seriously. We don’t just let the CEO or the board tell us quarterly or annually the ‘amazing performances they achieve’. No! If we have a question, we jump in. We have an active ownership sense. We aren’t involved in the day-to-day operation. But we look at it with a microscope from an owner’s point of view.
Can you share any recent examples of instances where you hesitated to approve an investment or bank loan request from an SOE?
Absolutely. There are requests we have rejected completely. There was a huge investment opportunity, a really wonderful investment that EIH would be very excited about. They have zero debt and can go and borrow substantial amounts from the market as well. But we identified their financial control risk and the business projection they put in front of us was not satisfactory . So, we rejected [the request]. We rejected another company’s investment plan after having it studied by external industry experts, because it sounded too broad and wishful. We have a very serious assignment of not repeating the previous mistakes of these SOEs.
What sectors are those companies in and how frequent are rejections?
I won’t be able to delve into the sectors. It is confidential business information.
Regarding frequency, it is not like we keep tabs and we say ‘we reject this much and we approve that much’. It is not how we do it. And this rejection is not also a final rejection. It is our way of communicating with them to correct it. What I wanted to emphasize is that we are not a stamp of approval. Our portfolio companies are divided into different sectors. Each cluster has its own director here. Each portfolio director is responsible for the day-to-day operations and reports of the enterprises in that sector. They look at them through a microscope and are able to make suggestions.
The enterprises under your purview are in a diverse range of sectors. How many staff do you have?
We have 57 right now. But we are growing. Also, the system allows us to be effective. We are not regulators. We are owners on behalf of the public. EIH can invest. That is a departure.

As CEO, what are your overall impressions based on the details of the performances you have access to and the in-depth dialogues you conduct with SOE boards and CEOs?
One of the things that I came to find impressive is the history of the SOEs. It is the history of Ethiopia. I found out in the dialogue that Filwuha [Spa Service Enterprise] used to be managed by Emperor Menelik II himself. The Emperor was its General Manager. Learning about how the Ethiopian Lottery Service was established and how the CEOs used to deal with convincing the Ministry of Finance and Emperor Haile Selassie I to get the required support whenever they faced a budget deficit; this is all our history.
I have learnt as an individual citizen that the history of my country [economic history] sits with these SOEs. That makes you more responsible; very careful when you make decisions. My role is to make sure that this country continues. Ethiopian Airlines has been here for 70, 80 years, and my role is to make sure that it continues for the next 100 years, by maintaining its history and supporting its growth.
Prior to your appointment as CEO of EIH, particularly during your time as an advisor to the Ministry of Finance [between 2018 and 2022], you appeared to be an aggressive proponent of SOE privatization. At the time, concerned economists shared the same perspective you are expressing now. Does this mean you have completely changed your mind about SOEs?
There is a complete misunderstanding about what the government’s policy was. As far as I know, the government does not have a privatization policy. It is a ‘state-owned enterprises reform policy’ instead. That is what I worked on. Since 2018, the government has worked on a state-owned enterprises reform policy not privatization policy.
You [officials of the Ministry of Finance] did officially announce the government’s decision to privatize companies, including some of the most successful ones, as evidenced by public debates you held and documents your team prepared. Correct?
Yes, there is a privatization aspect in the SOE policy as an [optional] output of the strategy. My argument is that when the government makes a decision to privatize a certain asset, for example the partial privatization of Ethio telecom, it comes with the reform aspect of it. The reform is what gave birth to the privatization. Privatization didn’t appear on its own.. It is a holistic view. That is my point.
I have always held a firm view that a typical example of the successful management of a state-owned enterprise exists in Ethiopia, and a typical example of an unsuccessful state-owned enterprise also exists in Ethiopia. It is your choice to pick and work on the one that succeeds and not with the one that doesn’t.
Take the example of the Sugar Corporation [Sugar Industry Group]. Does the government need to be in 30 sugar factories? I don’t think so. What do you do? You divest. If there are a few that you can keep as strategic assets, you divest the rest. But you don’t do that from the point of view of ‘privatizing’ a state-owned enterprise. People confuse the two. You initially define your ownership policy. If, based on that ownership policy, there is a need to divest, then you do so.
If you remember, many companies were thought to be [fully] privatized. But, have there been any companies privatized in the last five years? Zero! The government has not sold a single asset.

Including its most recent portfolio expansion, what is the current total value of assets under the management of EIH?
We are doing a total consolidated financial statement. This will be done in the next two months. Then we will be able to announce the total value. Right now, there are numbers here and there just based on asset value estimation but we can identify the correct net worth once the consolidated financial report is finalized.
Can you share the current debt levels of the SOEs? What is the most recent figure regarding the total debt burden of SOEs under EIH management? Which SOEs hold the highest debt burdens? Can you give us a breakdown of domestic and external debt?
Let’s put it this way: individual companies have certain debt figures, which are available on their debt numbers. It is true that one of the reasons behind the macro imbalances was unsustainable SOE debt. This includes debt owed by Ethiopian Electric Power, the Sugar Corporation, [the former] MetEC, and others. But many of those debts have already been transferred from several of the SOEs to LAMAC [Liability Asset Management Corporation] and now to the Ministry of Finance. The Ministry is issuing a 900-billion-birr debt instrument to make sure that CBE [Commercial Bank of Ethiopia] is capitalized. The World Bank has already approved 700 million dollars for CBE’s capitalization. Many now have either very insignificant or no debt. Companies like Ethiopian Shipping and Ethiopian Electric Utility have zero external debt. Those with debt now are the ones like Ethiopian Airlines and Ethio telecom, which are able to settle their debt sustainably.
Regarding figures, we don’t aggregate SOE debt numbers. We don’t put it that way. But, to me, the SOE debt narrative is outdated.
Nobody denies the role that SOEs have had in causing the macroeconomic imbalance. But we have introduced a mechanism to resolve this in a way that will also help the companies to grow and be forward looking.
Improving the commercial discipline of SOEs is said to be a key objective of EIH. Can you provide specific examples of how EIH has lived up to this goal since its establishment?
Our existence on its own has helped almost all of our SOEs; first to be commercially committed and second to limit the government’s policy involvement in SOEs, which has a direct implication. Take Ethio Lottery, which is an excellent showcase. It has gone through a significant transformation. It is coming with changes, including the logo. We are making sure that it delivers. Sugar estates such as Wonji Sugar Factory; we assigned a strong board and management to it. It is a great example of how EIH is engaging and helping companies transform. But our work is just getting started. We don’t want to brag and say ‘we have changed everything.’
The CBE’s dire situation was part of the agenda during negotiations with international financial institutions. The Bank’s governance structure, meaning its board, is typically composed of high-ranking government officials, who contributed to its troubles by prioritizing political decisions over sound financial principles. Recapitalization and reforming its governance were outlined in the agreement with the IMF, not only to save CBE but also the private banks. Tell us about the practical steps taken so far, EIH’s engagement in the process, and how well-positioned the domestic banking industry, including CBE, is to compete effectively with the impending entry of foreign banks?
One of the major steps taken was the recapitalization of CBE with the approval of the World Bank, which is a major step. Second, we have assigned three independent board members so that CBE can have independent voices. Third, the bank is left alone to make sure that it makes commercial decisions independently. Fourth, the NBE is providing the necessary guidance as to how a bank should be managed in a macro-financially prudent way and how it manages itself. And, fifth, private sector lending is growing significantly annually, which is a critical aspect.
Most importantly, the change of perception in CBE’s shift from a pure policy bank to a commercial entity is something we are working on.