
The issue of foreign currency shortages in Ethiopia has been a persistent economic challenge for decades. Whenever this topic arises in policy discussions or the news, there is a quote that immediately comes to mind for many Ethiopians who have closely followed and been affected by this problem over the years. That famous quotation comes from Sufian Ahmed, who served a record tenure as Ethiopia’s Minister of Finance from 1996 to 2015.
In 2009, while still in his role leading the country’s economic policy, Sufian boldly declared that Ethiopia’s lack of foreign exchange reserves would not be resolved within his lifetime. His words have proved prophetic, as the problem has only grown more severe with time. Though Sufian has long since exited politics and from his official position, the conditions he warned about have continued to plague Ethiopia’s economy.
As the years have passed since Sufian uttered that remark, the foreign currency shortage has worsened considerably. Despite persistent efforts by subsequent governments to address the imbalance through export promotion and attraction of foreign investment, foreign reserves remain dangerously low. Ordinary citizens and businesses still struggle with a lack of access to dollars and other hard currencies needed for imports.
RELATED POSTS
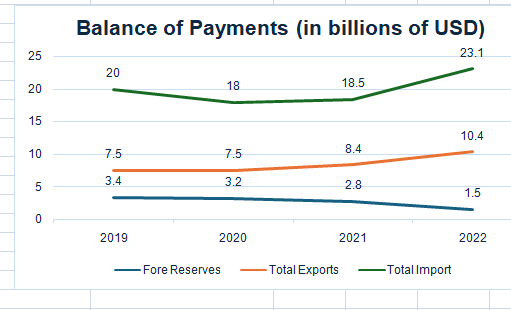
To understand the severity and longevity of Ethiopia’s shortage, it’s important to examine the scale of the imbalance over an extended period. Foreign reserves totaled just under one billion dollars in 2009 when Minister Sufian uttered his famous quote. By late 2017 when the last devaluation happened, reserves had declined to under half a billion dollars despite significant economic growth. Today reserves are a little above one billion according to National Bank of Ethiopia data, largely unchanged from over a decade ago.
This stagnation is alarming considering Ethiopia’s expanding population and economy. GDP has more than tripled to over USD 200 billion since 2009 while the population grew from over 80 million to over 120 million. Rising domestic demand means more imports are needed to fuel development yet reserves have failed to keep pace, worsening the shortage. The resources available to pay for essential imports like fuel, medicines and manufacturing inputs have hardly increased. Given projections of continued fast population growth, resolving this challenge is an economic imperative for Ethiopia’s sustained development.
Devaluation has traditionally been the main policy tool used by Ethiopian governments to address the shortage, with seven devaluations taking place between 2000-2017. The theory held that lowering the overvalued birr would stimulate exports and reduce imports by making local goods cheaper overseas and foreign items more expensive domestically. Yet despite multiple devaluations, forex inflow did not meaningfully rise as hoped.
Several factors help explain the limitations of repeated devaluations alone as a solution. Firstly, Ethiopia’s economic structure remains heavily import-dependent, with significant imports needed for manufacturing, construction, and agriculture due to underdeveloped local industry. Simply lowering prices was insufficient to overcome domestic supply bottlenecks hindering import substitution. Secondly, exports have historically relied on raw commodities like coffee exposed to volatile global prices, rather than higher-value processed goods less sensitive to exchange rate movements. Boosting non-traditional exports required extensive reforms not paired with devaluations.
The continued overvaluation of the birr also encouraged speculative behavior as some sought to profit from a perceived inevitability of future devaluations by stockpiling dollars on informal markets. This parallel market activity drained official reserves and undermined policy credibility. Lastly, large debt servicing obligations and outflows for other capital flight drained reserves, offsetting whatever stimulus devaluations provided. In short, one-off adjustments proved too narrow to shift Ethiopia from a structural deficit without complementary measures.
Current efforts and Factors that Need Attention
If we examine why previous devaluation measures did not work, a major reason is the failure to implement complementary sector-specific reforms. Supply-side problems were not addressed before exchange rate adjustments.The administration of Prime Minister Abiy Ahmed (PhD) that came to power in 2018 has acknowledged the limitations of such approaches and adopted a more comprehensive strategy.
The current administration has made some progress in areas like wheat, which saved over half a billion dollars annually, and manufacturing where import substitution reached two billion dollars last fiscal year according to industry ministry figures.
Another positive step was restricting unnecessary imports, which drained scarce forex resources under prior administrations. Previous adjustments ignored this while the current one banned even small items and old fuel vehicles to conserve funds.Previous devaluations also did not curb forex outflows from debt servicing and related expenses. The government’s debt restructuring, while taking longer than expected, moved in the right direction in this regard.
Efforts to secure large concessional loans from the IMF and World Bank, which could reach USD 10 billion and boost reserves above Kenya’s eight billion dollars level, are underway. Prime Minister Abiy outlined challenges in obtaining this critical financing previously but recent reports suggest the country is edging close to secure the much needed fund. While current policies signal a more thoughtful approach than the past, several critical factors require attention moving forward.
Way Forward
Reducing imports depends on accelerating local production to meet demand. Targeted support through subsidized credit, training, technology transfer and special economic zones can help overcome supply chain deficits constraining sectors like manufacturing, agro-processing and construction materials industries.
Loose oversight has facilitated smuggling, tax evasion and round-tripping that drain reserves. Tighter border, customs and licensing controls combined with anti-corruption reforms can better mobilize export earnings and imports revenues for development.
Beyond traditional crops, identifying and cultivating new promising exports based on specific regional/global market analysis can reduce vulnerability to commodity price volatility. Consumer goods, automotive components, horticultural and processed agricultural products show exports potential with appropriate support.
Fast population growth means hundreds of thousands require jobs annually.
Integrating underemployed youth and women into productive activities both reduces consumption needs and generates foreign exchange through remittances when employed overseas. Targeted skills and entrepreneurship programs are thus important complements to infrastructure development alone.
Deeper cooperation on standards harmonization, trade liberalization, infrastructure connectivity and financial/payment system integration with neighbors like Sudan, South Sudan, Kenya and Djibouti expands Ethiopia’s economic space and export opportunities vital for sustained currency inflows. The nascent African Continental Free Trade Area presents potential long-term benefits if implemented well.
Recurring domestic unrest and border disputes sap investment, disrupt trade flows and drive capital flight abroad as uncertainty rises. Domestic political reforms and negotiated settlements of outstanding issues with rebel groups are also essential to foster investor confidence and the currency inflows development requires.
While the measures outlined show promise to reduce Ethiopia’s structural deficit, a managed float of the birr will also likely be necessary to properly price the exchange rate over the long run. However, any liberalization of the birr must be carefully implemented with complementary safety net programs and macroprudential regulations in place. The government will need to enhance its capacity to intervene in currency markets and strengthen oversight of parallel trading if speculation emerges in response to a float.
Building robust reserves acts as a critical buffer against potential instability during a transition. If adopted through prudent, multisectoral efforts as a package, there is real potential for Ethiopia to finally gain command of its foreign exchange resources to sustainably fuel development rather than perpetually plagued by shortages.
With the gap between the official and parallel exchange market remaining around 100 percent for over a year now, the exchange rate adjustment cannot be left as is. Maintaining such a large divergence incentivizes speculative behavior, capital flight and undermining of policy credibility – all of which drain the foreign reserves Ethiopia is struggling to boost. Reforms are needed to establish a realistic, market-determined exchange rate in both official and informal markets in order to make progress on Ethiopia’s elusive quest for sufficient foreign exchange.
Samson Berhane is an economics graduate with expertise in business and economic reporting and communications. He can be reached at [email protected]. The views expressed in this article are his own and do not represent the opinions of the institutions he is affiliated with nor that of the magazine.