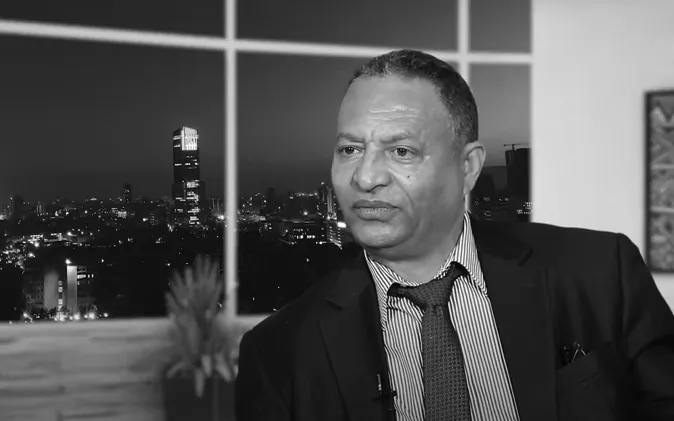

With decades of experience steering some of Ethiopia’s biggest banks, Eshetu Fantayeh as a unique vantage pointon the development of the country’s financial industry. He has witnessed the ebbing flows of the country’s vibrant financial sector firsthand. As his impressive resume shows, Eshetu is no stranger to leadership roles, having previously served as president of institutions like Ahadu Bank and Buna Bank.
Before helping establish innovative players like Goh Mortgage Bank, Eshetualso served as vice president at Awash International Bank. With his background in banking and finance from the University of Rome Tor Vergata, Eshetu offers informed perspectives drawn from both academic training and hands-on leadership.
The Reporter Magazine met with Eshetu to discuss the future potential of Ethiopia’s banking sector from the view of a seasoned industry insider. EXCERPTS:
RELATED POSTS
The Reporter Magazine: Bank performance has been declining according to recent annual reports. Some banks have seen lower profit margins and dividends, while new banks, especially de novo banks, are reporting losses. Experts expect the industry won’t maintain its high profits of the past due to increased competition. What conditions do local commercial banks need to be successful moving forward amidst these competition?
Eshetu Fantaye: As the saying goes, “beauty is in the eye of the beholder,” the success of banks in a developing country like ours depends on how we define “success.”
This calls for an extensive debate among all stakeholders, including regulators and consumers, on what should drive operators in our banking and financial system. We need to develop a performance indicator, a holistic Key Performance Indicator (KPI), for our banks or operators in the system to guide their growth trajectory towards what we have collectively agreed upon as “success.”
The regulator should play an active role in establishing the elements that will help banking business owners/operators develop their business models and objectives, aligning them with the greater goals of the country and the welfare of its people.

Unfortunately, this has been lacking in our system for a significant period of time.
For instance, the omission of this discussion during the PASDEP, GTP-I, and GTP-II has led to a development financing fiasco that the country faces, ultimately resulting in the downfall of the three Policy Banks owned by the country (Commercial Bank of Ethiopia, Development Bank of Ethiopia, and Construction and Business Bank). Even in the recent Ten-Year Perspective Plan, this omission has not been adequately addressed, giving rise to intricate development financing issues that are leading to serious inflation and rapid currency depreciation.
So, to evaluate success objectively, the government, regulators, shareholders, and various stakeholders in the system must come to an agreement on KPIs that can be used to measure the “success” or lack thereof in the system.
In the recent past, particularly since 2010, the growth trajectory of the banking sector has achieved commendable milestones in terms of geographic coverage and, to some extent, access to services. However, it has failed to bring about significant depth in the system. Furthermore, the system has not been able to ensure fair and equitable distribution of services among important segments of our society. In fact, the growth trajectory of the system has been plagued by numerous unaddressed dichotomies.
Without proper regulation and adjustment, the system has consistently favored certain segments of society, making them the primary beneficiaries, while leaving other segments as outright losers. This winner-loser dichotomy has been a pervasive and visible characteristic of the system since its early days.
Unfortunately, regulation, despite the liberalization of the sector in 1994, has failed to correct these multiple dichotomies. In some cases, it can even be said that it has contributed to the creation and perpetuation of such disparities.
Dichotomies such as the urban-rural divide, savers-borrowers, productive-non-productive segments of the economy, producers-exporters, exporters-importers, and fixed-income earners versus business income owners readily come to mind as instances of these disparities.
As someone who keenly observes the system, what corrective measures do you suggest should be implemented to effectively tackle the issue at hand?
I would say that regulation should, first and foremost, aim to remove or resolve the outcomes of these dichotomies. Otherwise, these and other dichotomies will continue to have a severely debilitating socioeconomic and political impact. In extreme cases, they may even threaten the very existence of the nation-state as we know it. Therefore, any success of the system must also be viewed in terms of its ability to avoid and/or contain the negative consequences of these dichotomies.

The second important condition for the sector to flourish is a “level playing field.” Currently, such a level playing field does not exist due to banks operating with opaque mandates within the system. The formation or the very establishment history of our banks are the causes of the harmful lack of transparency in their mandates. This necessitates a revisiting of the banking proclamation of the country.
The existing proclamation needs to be redrafted to clearly define the mandates of all banks, including those operating to achieve policy objectives. Banks and financial institutions operating for policy objectives, even if they serve important causes, must be ring-fenced and prevented from casting a shadow on the operations and growth potential of other market participants.
If the mandates and business permissions are crafted with policy banks of color and cause in mind, or if regulations are executed with the tacit welfare of these entities in mind, the development of the financial system will inevitably be stunted. Additionally, when the full potential of the sector is not considered holistically, significant resources will remain outside the country’s development initiatives and objectives, which is detrimental in multiple ways.
Above all, the proclamations, regulations, and directives governing the financial system and development finance should serve as instruments for connecting economic operators in the country, rather than causing fragmentation within the nation’s economic system and the operations of different actors in isolated regions.
Thirdly, our education system must produce capable and well-educated human resources capable of guiding our banks along their projected growth path. Currently, there is a severe shortage of human talent equipped to manage the banking system in a 21st-century fashion. The regulator, banks, and the education system must work hand-in-hand to address this gap.
Fourthly, regulations must guide banks and/or be forward-looking to help them fulfill their proper role in the IGAD, COMESA, and the broader AfCFTA area. The continental trade system and the ongoing economic integration initiative are opportunities that the country’s commercial banks and financial operators should not miss, unless facilitating inter-regional and continental trade constrains us.
Currently, the country faces constraints due to a lack of Correspondent Banking Relationships (CBR), resulting in punitive costs for our manufacturers, importers, and exporters. Unless our commercial banks and the entire financial governance system are encouraged to focus on these inter-regional and continental responsibilities, our economy and trade relationships will suffer. And if we do engage in trade, we will once again be exposed to punitive trade facilitation fees that handicap the competitiveness of our producers, importers, and exporters.
There is also a strong need to revamp the entire governance system of the sector to make it more responsive to the interests of all stakeholders and enable it to meet the country’s needs. As someone with insider experience who has been part of the system for a long time, I am not happy with the current governance system.
In some financial sector operators, the existing governance system is insular and severely flawed. It is heavily influenced, sometimes visibly, by interest groups with malicious and self-serving intentions, and the consequences of this are alarming for the system. The broken system has even allowed these malicious interest groups to work against the interests of numerous unrepresented stakeholders.
The breakdown in governance within certain institutions has reached a critical condition such that it could lead to individual instances of failure and, if left unaddressed for too long, could potentially undermine the entire system.
There are indications that suggest a hostile takeover (even bank capture) has been planned and executed by forceful interest groups with malicious intent in some of our banks. This is causing havoc in the operations of these banks and hindering their realization of their full potential both domestically and internationally.
So, the longer this broken governance system persists and remains unaddressed, the immense damage it will inflict upon the country and its people. The reputation of some of our banks has already been tarnished internationally due to the malicious activities of these interest groups at the governance level.
Ultimately, the damage caused by the broken governance system will go against the benign interests of taxpayers and the country as a whole, who have no involvement in the governance system or its broken variant.
The success of our banks in the future, both domestically and globally, will heavily depend on the active implementation and evolution of a robust governance system that is accountable to all stakeholders, as well as the active supervision and enforcement of governance rules in the interest of the welfare of the population and the country’s economy.
The sixth and final point I would like to emphasize is that the regulator must guide our commercial banks to compete when necessary, but also foster cooperation when national advantages are at stake. There are numerous instances where cooperation among our banks is essential for the benefit of the country as a whole and their respective customer bases in particular.
Success is ensured when banks in the system operate within networks, and this is especially important for their regional and international operations.
What is your evaluation of the government’s Foreign Banking (FB) entry initiative and its potential impact? How does the current performance of the banking industry influence the interest of foreign banks in entering the market?
Overall, I may say that it is time to allow the entry of FBs into the country. If for nothing else, this would result in the infusion of liquidity for credit operations and improve the flow of foreign capital and knowledge into the country. However, achieving this requires a focused and concerted effort from regulators and the government.
While saying their entry is timely, I want to emphasize several points. First, the modalities of entry outlined in the Proclamation must provide detailed information on the mandate and permitted business activities for FBs. Second, there is a need to properly specify the context of entry, mandate, and permitted businesses to ensure that the opening up of FBs adds true value and enhances the country’s financial ecosystem.

Third, it is crucial to protect the interests of the millions of shareholders and stakeholders. This includes safeguarding the interests of shareholders who have contributed their hard-earned and limited resources to create and develop banks, under the policy protection provided by the government in the past. Fourth, allowing FBs to enter the system through the two modalities indicated in the amended proclamation (Subsidiary and Branch Banking, with or without domestic incorporation) would lead FBs to focus on operations that are already the core activities of domestic banks in the sector. This may be detrimental in the short run to the shareholders, stakeholders, and the country as a whole.
Therefore, the various modalities of entry must be carefully considered and debated by well-informed practitioners who have good intentions.
Finally, the expansion of FBs’ mandates and permitted business activities must be sequenced and gradual to avoid the harmful impacts seen in other countries, including those in Sub-Saharan Africa.
My argument presented above is based on the objectives of the government policy document, which positions FBs as a value-added venture that complements existing sector players. The government policy aims to increase and expand the sector’s capacity in various ways, including expanding the credit market, sourcing foreign currency, introducing higher technology and innovative operations and instruments, and creating jobs.
To achieve these objectives, the government and regulators must ensure that FBs inject more capital into the sector, particularly in foreign currency, and that FBs initially expand credit in the system using their own sources rather than relying on domestic resources, exports, and international remittance operations. Additionally, the operational mandate and permitted business scope of FBs must be carefully sequenced and introduced to maximize their beneficial impact on the macro-economy and achieve the desired outcomes envisioned by the government.
In terms of sequencing, I recommend that FBs should not initially be allowed to engage in domestic resource mobilization, exports, and international remittance operations, as these activities are already the core activities of domestic banks. The entry of FBs should be designed in a way that complements the operations of domestic banks rather than immediately and directly competing with them, at least in the early stages.
Regarding the current interest of FBs in entry, it is currently difficult to determine the exact size of this interest and its implications. However, I believe there will be some entities interested in venturing first to take advantage of the wide opportunities available in the country.
My only concern is that due to the instability in our country, only high-risk takers with little substantive value may venture, limiting the choices available to our country. It is crucial that we adopt a selective approach when granting entry to foreign banks.
Considering the present performance of the banking industry, what can be inferred about the prospective performance of our banks following the entry of Foreign Banks? Will their presence have a positive impact on the banks already operating in the country?
In my opinion, if the opening up is methodically done with some of the cautions I mentioned here and that other professionals have mentioned elsewhere, it would be beneficial for the system in general, including our own banks operating in-country.
As you may note, due to the 20 percent Bill Purchase rule and the 14 percent Credit Cap recently imposed by the regulator to counter inflation, the overall economy is operating under a “credit-constrained” model.
This was deemed necessary not because growth is not the regulator’s mandate, but because inflation poses a much wider menace to the economy moving forward. Furthermore, the country has been living under a binding constraint of foreign currency for far too long, which has now become a cause for the contraction of many sectors of the economy that depend on foreign currency as an input source.
Given the environment I described above, the entry of foreign banks may be very helpful at this juncture in addressing the two severe constraints that have shackled our economy from reaching full throttle. This change, if executed properly, can also provide the impetus required to transform domestic banks and correct the Balance of Payment problem that bedevils our country.
As in many instances, the devil is in the details.
We need to craft the entry of foreign banks in such a fashion that they complement our development efforts and do not exacerbate our problems. This can only happen when the regulator is properly empowered, educated, and capacitated in all aspects.